Pay Vendors From a Mobile App: What Businesses Need Before They Tap Send
Disclosure: This article was published as part of a paid partnership with Zil Money. The author is an independent contributor.
Businesses can pay vendors from a mobile app, but a good vendor-payment workflow requires more than choosing a recipient and tapping a button.
The payer still needs the correct vendor information, an approved amount, the appropriate funding source, and a payment method the vendor can receive.
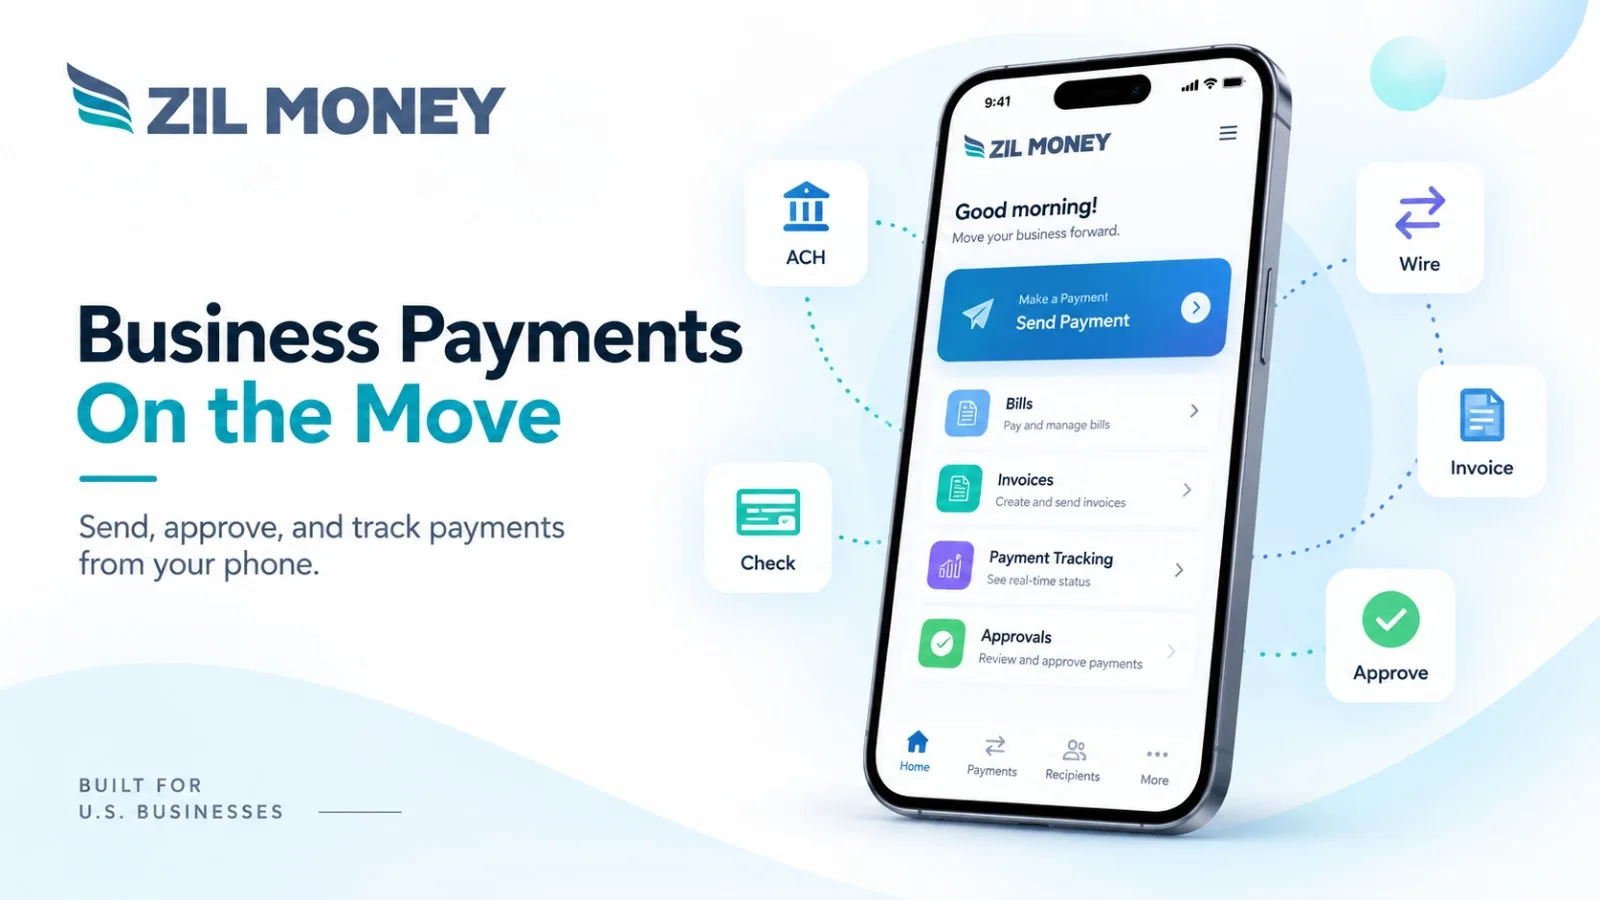
Zil Money’s current Mobile Payments page says businesses can review and release vendor payments from its app using supported methods that include ACH, wire transfers, checks, and other available workflows.
First Confirm the Vendor
Mobile access does not change the need to verify who is being paid.
Before releasing a transaction, confirm the vendor name, amount, invoice or payment purpose, and recipient details.
This becomes especially important when payment instructions have recently changed.
Nacha’s B2B ACH guidance specifically advises businesses to verify the company being paid and independently confirm changes in payment instructions before sending money.
That is useful guidance whether the payment is initiated from a phone or desktop.
Choose the Right Delivery Method
Different vendors accept different payment methods.
ACH may work for a recurring supplier that has provided bank information.
A check may work for a vendor that still uses paper payments.
A wire may be appropriate for a transaction where that payment rail fits the business need.
Zil Money’s mobile app supports several of these methods within the same business-payment environment.
The phone is the access point. The underlying payment rail still determines many of the transaction’s requirements and timing.
A Credit Card Can Be the Funding Source
Some businesses want to use a business credit card even when the supplier does not accept cards directly.
Zil Money’s current mobile product page describes eligible card-funded workflows where the business uses a card and the vendor receives funds through a supported method such as ACH, wire, or check.
That distinction is important for both users and search engines.
The vendor is not necessarily processing a credit-card payment.
The card is funding the transaction on the payer’s side.
Understand the Card Fee
Card funding has a cost.
Zil Money’s current support documentation lists a 2.9% credit-card processing fee, with additional charges potentially applying depending on the selected payment method.
Businesses should verify current pricing when making the transaction because fees and product conditions can change.
A mobile interface does not change the economics of the payment.
The company should still decide whether paying the fee makes sense for the particular vendor invoice.
Keep Approval Controls in Place
A business may allow an employee to prepare a vendor payment but require a manager to release it.
That control should remain in place when payments move to mobile.
The convenience of approving from a phone can be valuable for owners and managers who travel, work across locations, or spend time away from a desk.
But faster access should not mean skipping review.
Check the payee, amount, payment method, funding source, and related invoice before approving.
Review the Transaction After Sending
Vendor questions often arrive after payment has been submitted.
Zil Money’s current mobile documentation says users can view payment status and searchable transaction history through the app.
That gives authorized staff another way to respond when a supplier asks about a payment.
Payment status should still be interpreted according to the selected rail. A mailed check and an ACH transfer do not move through the same process.
Mobile Vendor Payments Are About Access
Paying vendors from a mobile app is useful when the business needs to keep AP moving without requiring every approver to be at the office.
Zil Money can be evaluated for this workflow because its mobile app connects vendor payments with multiple payment options, existing payees, transaction records, and supported accounting connections.
The strongest mobile process still follows the same basic rule as desktop AP:
verify the vendor, approve the amount, select the right rail, understand the fee, and keep the payment record.
Zil Money, is a financial technology company, not a bank. Banking and money movement services are provided through partner financial institutions and licensed service providers. FDIC insurance coverage applies only to eligible deposit products and accounts, and is subject to applicable terms, conditions, limitations, and requirements. Additional information regarding partner institutions, products, and services is available in the applicable terms and agreements.