Posted on

Which Siding Holds Up Best to Colorado Hail? A Style-First Guide to Materials and Colors

A house’s exterior is the first thing anyone sees and the last thing most owners think about until a storm rolls through. On Colorado’s Front Range, that storm is rarely a question of if. Hail season arrives each spring, and a facade that looked crisp in April can look pockmarked by July.

The good news is that you do not have to choose between a beautiful exterior and a durable one. The best siding for this climate can be warm, textured and full of character. It simply has to be chosen with the weather in mind.

Why Front Range Homes Need a Tougher Skin

The numbers explain why homeowners here think about siding differently. The Rocky Mountain Insurance Information Association has long ranked Colorado No. 2 in the nation for hail insurance claims. State Farm alone reported $521 million in Colorado hail claims in 2024, and a single May 2024 storm caused at least $1 billion in damage, according to NOAA.

Hail is only half the story. At high altitude, the sun is intense, and ultraviolet light fades color and dries out finishes faster than it does at sea level. Add dramatic temperature swings between day and night, and siding here has to handle impact, sun and constant expansion and contraction.

The Materials, Ranked by Beauty and Backbone

Fiber Cement

If you want the look of painted clapboard with the toughness of masonry, fiber cement is the designer’s favorite. It carries crisp shadow lines, takes wood-grain textures convincingly, and its density stands up well to hail. Factory-applied finishes resist UV fading, which matters under Colorado’s sun.

The look: Classic farmhouse lap, board and batten, or smooth modern panels.

Keep in mind: It is heavy and needs experienced installers.

Metal

Steel siding has moved well beyond the barn. Standing seam panels and wide flat profiles give a home a clean, architectural edge, and baked-on finishes hold color for years. Steel resists dents far better than aluminum, so gauge matters.

The look: Mountain modern, especially in charcoal, bronze or weathered finishes.

Keep in mind: Thinner gauges can dent in severe storms.

Stone and Stone Veneer

Nothing grounds a house like stone. Used as a wainscot along the base of a home, around an entry or wrapping a chimney, it adds weight and texture that softer materials cannot match. It is also nearly indifferent to hail.

The look: Stacked ledgestone in warm grays and tans echoes the foothills.

Keep in mind: Full stone is costly, so many homeowners use it as an accent.

Wood

Cedar and other natural woods bring unmatched warmth, and they age into a silvery patina that suits the Colorado landscape. Wood can take a hit, but it demands upkeep in dry, sunny air, where finishes break down and boards can check or split.

The look: Rustic, cabin-inspired or Scandinavian minimal.

Keep in mind: Plan on regular staining or sealing.

Vinyl

Vinyl remains the budget-friendly option and comes in a wide range of colors and profiles. Standard vinyl can become brittle in cold weather and crack under hail, so insulated or thicker premium vinyl is the better choice here.

The look: Traditional lap in soft neutrals.

Keep in mind: Dark vinyl colors are more prone to heat and sun issues.

Color Advice for High-Altitude Light

Colorado light is bright and clear, which makes colors read cooler and lighter than they look on a paint chip. A few guidelines help:

  • Go a shade deeper than you think. A mid-tone gray often reads pale in full sun.
  • Favor warm undertones. Greige, putty and warm taupe sit comfortably against the plains and foothills.
  • Choose UV-stable finishes for dark colors. Deep charcoals and blacks look striking but fade faster without a durable factory finish.
  • Let the landscape lead. Sage, stone and muted clay tones connect a house to its setting.

Mixing Materials Without Losing the Plot

Some of the most handsome homes on the Front Range combine two or three materials. A stone base, fiber cement lap across the main body and metal accents on a porch or bump-out can look layered and intentional. The rule of thumb is to limit yourself to three materials and repeat each one at least twice around the house so the design feels deliberate.

Combining siding materials also has a practical benefit. Stone at the base protects the zone most exposed to splashback, snow and wind-driven hail.

After a Storm: Protect Your Claim

When hail hits, damage to siding often travels with damage to the roof, gutters and window screens. Take dated photos of every elevation right after the storm, note the size of the hail if you can, and call your insurer before any repairs begin. Ask about matching as well. Replacing only a few damaged panels with a newer product can leave a visible patchwork.

Choosing a Siding Company in Aurora

For homeowners in Aurora, the most useful filter is simple: hire a contractor who handles roofs and siding together and understands hail claims, since one storm tends to damage both. Aurora spans parts of Arapahoe, Adams and Douglas counties, so a local crew should also know the permit expectations that come with each jurisdiction.

Pinnacle Roofing Associates is one example that fits that filter. The company has served Aurora and the Denver metro since 2008, and its team brings more than 25 years of combined experience. Along with roofing and hail damage repair, it installs stone, wood, metal and vinyl siding and helps homeowners work through storm-related insurance claims. For Colorado homeowners comparing a siding company Aurora Colorado residents can trust with both halves of a hail repair, that roof-plus-siding experience is the detail worth asking every contractor about.

The Takeaway

The right siding for a Colorado home is the one that suits your architecture and survives your weather. Start with durability, then have fun with texture and color. A facade built for hail can still be the prettiest house on the street.

Posted on

What Happens During an IRS Audit? Process, Deadlines & Rights

An envelope from the Internal Revenue Service can ruin an afternoon. Yet most IRS letters are not full audits, and most audits are resolved through the mail. Knowing which letter you have, which deadline applies, and who can represent you makes the difference between a quick fix and a costly mistake.

This guide explains how IRS audits work, what triggers them, the deadlines that matter, and how to decide whether you need a tax attorney, a CPA, or an enrolled agent.

Key Takeaways

  • Fewer than 0.4% of individual tax returns were examined in fiscal year 2024, according to IRS Data Book figures.
  • Most audits are correspondence audits handled entirely by mail.
  • Many IRS notices carry response windows of 30 days, and a Notice of Deficiency gives you 90 days to petition the U.S. Tax Court.
  • A tax attorney offers attorney-client privilege, which also covers matters that could turn criminal. The federal tax practitioner privilege available to CPAs and enrolled agents does not.

How Common Are IRS Audits?

Audits are less common than most people fear. In fiscal year 2024, the IRS closed 505,514 tax return audits, which produced $29 billion in recommended additional tax. Fewer than 0.4% of individual returns were examined. The rate climbs sharply at the top: returns reporting $10 million or more in total positive income faced an examination rate of about 7.9%.

Low odds do not mean low stakes. An audit that finds unreported income can lead to back taxes, interest, and penalties that grow the longer the matter stays open.

Types of IRS Audits

Audit Type How It Works Typical Scope
Correspondence audit Conducted by mail. The IRS asks for documents on specific items. One or two line items, such as a deduction or credit
Office audit You or your representative meet an IRS employee at a local IRS office. Several items, often business or rental income
Field audit A revenue agent visits your home or business to review records. Broad review of books, typically for businesses

Correspondence audits make up the large majority of examinations.

What Triggers an Audit?

The IRS relies heavily on automated matching. Employers, banks and brokers file information returns such as Forms W-2 and 1099, and the IRS compares those forms against what you reported. When the numbers do not match, the Automated Underreporter program sends a notice, often a CP2000, proposing changes.

Other common triggers include:

  • Business expenses that look large relative to income
  • Rental losses and home office deductions
  • Refundable credits claimed without full support
  • Large charitable deductions, especially noncash gifts
  • Unfiled returns, which can lead the IRS to prepare a substitute return using third-party data

What to Do When You Get an IRS Letter

  1. Identify the notice. The notice number sits in the top or bottom right corner. A CP2000 proposes changes based on mismatched data. A letter scheduling an interview signals an office or field audit.
  2. Mark the deadline. Response windows are short. Missing one can let the IRS finalize its proposed changes without your input.
  3. Pull your records. Gather the return in question, bank statements, receipts and any forms the notice references.
  4. Do not overshare. Answer the specific items requested. Volunteering unrelated information can widen the scope.
  5. Decide on representation. You can respond yourself, but you also have the right to be represented. An authorized representative files Form 2848 and can speak with the IRS on your behalf.

Deadlines That Matter

Deadline What It Means
Response date on the notice Often 30 days for proposed-change notices such as a CP2000
90 days after a Notice of Deficiency Window to petition the U.S. Tax Court without paying the tax first (150 days if the notice is addressed to you outside the U.S.)
3 years from filing General period the IRS has to assess additional tax
6 years from filing Extended period when income is understated by more than 25%

Tax Attorney vs. CPA vs. Enrolled Agent

All three can represent you before the IRS. The differences show up in privilege, litigation and complex exposure.

Professional Can Represent in Audits Can Litigate in Tax Court Privilege
Tax attorney Yes Yes Attorney-client privilege, including criminal matters
CPA Yes Only if admitted to practice before the Tax Court Limited federal tax practitioner privilege, which does not apply in criminal matters
Enrolled agent Yes Only if admitted to practice before the Tax Court Same limited federal privilege

A CPA or enrolled agent is often enough for a simple correspondence audit about a single deduction. A tax attorney makes more sense when:

  • The audit could expose fraud or willful underreporting
  • You have years of unfiled returns
  • Foreign accounts or FBAR issues are involved
  • The case may head to IRS Appeals or the Tax Court
  • The IRS has started collection action such as liens or levies

How to Choose a Tax Attorney

Look past general practice lawyers who list tax as one service among many. Strong candidates share a few traits:

  • Focused tax practice. Audits, appeals and collections should be the core of the work.
  • IRS procedural knowledge. Attorneys who understand how examiners and Appeals Officers evaluate files can anticipate the next request.
  • Tax Court experience. If your case may be litigated, your attorney should be able to take it there.
  • Direct attorney involvement. Ask who will handle your file day to day.
  • Clear fee structure. Ask whether the matter is billed hourly or at a flat fee, and what is included.

Finding Help in Collin County

These criteria apply anywhere, including growing areas such as McKinney and the rest of Collin County. Taxpayers facing an audit should focus less on location alone and more on whether an attorney has experience with the specific IRS procedure involved.

For example, someone looking for a tax attorney mckinney tx can evaluate counsel based on prior IRS experience, familiarity with appeals, and the ability to handle a dispute if it reaches the U.S. Tax Court. Gregory Law Group is one local example because its attorneys previously worked in the IRS Office of Chief Counsel. That background is relevant when comparing attorneys for an IRS audit, but it should be considered alongside the facts of the case, the attorney’s role, and the type of representation required.

Bottom Line

An IRS audit is a process with rules, deadlines, and rights on your side. Read the notice, mark the deadline, gather records, and answer only what is asked. For a single mismatched form, you may handle it yourself or with your tax preparer. When the dollars are large, the years are many, or criminal exposure is possible, bring in a tax attorney before you respond.

This article is for general information and is not legal or tax advice. Consult a qualified professional about your situation.

Posted on

Can Carpet Be Repaired Instead of Replaced? What to Look for Before You Tear It Out

Wall-to-wall carpet does quiet work in a home. It softens footsteps, warms a bedroom on a January morning, and gives a living room the hushed feeling that hard floors never quite manage. So when a ripple starts to run across the family room, or a candle leaves a scorch mark by the hearth, the first instinct is often to price out a whole new floor.

Hold that thought. A surprising amount of carpet damage is local, mechanical, and fixable. The trick is knowing which problems live on the surface and which ones point to a floor at the end of its life.

Start With the Question Every Installer Asks

Before anyone talks about patches or seams, a good technician will ask one thing: is the carpet itself still healthy?

Healthy carpet has a backing that stays bonded to the face fibers, pile that springs back when you press it, and no lingering odor from past water damage. If those three boxes are checked, most of what bothers you is a repair job. If the backing is crumbling or the pile is crushed flat from wall to wall, repair only buys time.

Wrinkles, Ripples and That Wave by the Sofa

Ripples are the most common complaint, and the most fixable. They show up for a handful of reasons:

  • The carpet was never stretched tight. Many installs rely on a knee kicker alone, which cannot pull a large room taut. A power stretcher braces against the opposite wall and pulls the carpet evenly onto the tack strip.
  • Heavy furniture was dragged instead of lifted. A loaded bookcase pushed across a room can pull carpet off its strips.
  • Indoor humidity swings. Carpet backing relaxes and tightens as the air changes, and loose installs show it first.

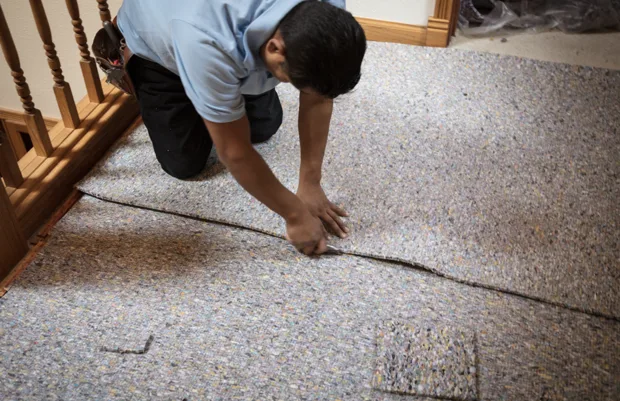
The fix is re-stretching. A technician releases the carpet from the tack strip, pulls it tight with a power stretcher, re-hooks it, and trims the excess. The room looks newly laid, and you keep the carpet you chose.

A quick test: push the ripple with your foot. If it moves or flattens and then returns, it is a stretching problem. If the surface feels crunchy or powdery underneath, the backing may be delaminating, and that is a different conversation.

Burns, Stains and Pet Damage

Some marks refuse to leave. Bleach spots, iron burns, and corners a new puppy chewed through will not clean out. This is where patching earns its reputation.

A skilled patch starts with a donor piece, often cut from inside a closet where no one will notice. The damaged section comes out, the donor goes in with seam tape, and the technician lines up the pile direction so light hits both pieces the same way. Done well, you have to hunt for it.

Two details decide whether a patch disappears:

  1. Dye lot and wear. A donor from a closet has seen less sun and foot traffic, so a light cleaning of the surrounding area helps the colors meet.
  2. Pile direction. Run your hand across the carpet. The smooth direction must match on both sides of the seam.

Seams That Peak or Pull Apart

A visible seam line, or one that has started to split, is typically a failed tape or an adhesive that let go. Re-seaming with fresh heat-bond tape closes the gap and flattens the peak. In doorways, a frayed edge can be re-bound or finished with a new transition strip, which also stops the unraveling from creeping into the room.

When Replacement Is the Better Choice

Repair is not always the kind answer. Consider replacing when you see:

  • Backing that crumbles or feels gritty across large areas
  • Pile that stays matted in every traffic lane, not only in one hallway
  • A lingering musty smell after a flood, which can point to moisture trapped in the pad
  • Several repairs needed in one room, where the combined cost starts to approach a new install

A Note on Warranties

This part gets overlooked. Carpet makers tie their warranties to proper care, and the Carpet and Rug Institute keeps a list of service providers that meet manufacturer standards. A repair done with the wrong method can put that coverage at risk. Ask any technician whether they work to manufacturer specifications before they touch your floor.

If You Are Weighing Repair in Denver

Colorado’s Front Range adds its own twist. Denver’s semi-arid air, combined with furnaces running through the long heating season, pushes indoor humidity up and down across the year. Carpet that was stretched loosely at install tends to show those swings as waves in spring and fall.

That makes two criteria matter most for homeowners in the City and County of Denver: a crew that uses a power stretcher rather than a knee kicker alone, and one whose methods keep your manufacturer warranty intact. For Colorado homeowners comparing options, that combination of warranty-safe methods and certified denver carpet repair work is the standard worth asking every provider to meet.

Living With Carpet After the Repair

Once the floor is tight and whole again, a few habits keep it that way:

  • Lift, never drag. Slide furniture on felt pads or lift it with help.
  • Rotate the room. Moving a sofa or bed a few inches every year shifts wear away from the same path.
  • Layer where it counts. A flat-weave runner in a busy hallway protects the carpet beneath and adds pattern to a quiet corridor.
  • Blot, do not scrub. Scrubbing a spill untwists the fibers and leaves a fuzzy patch that reads as a stain.
  • Schedule cleaning. Grit works like sandpaper at the base of the pile, so regular professional cleaning extends the life of the fibers.

The Takeaway

Carpet rarely fails all at once. It loosens, it snags, it takes a burn in one spot while the rest of the room stays lovely. Before you commit to tearing it out, walk the floor with someone who can tell a stretching problem from a worn-out backing. Often, the room you love is one afternoon of repair away from looking like the day it was laid.

Posted on

What Causes Electric Gates to Stop Opening or Closing Properly?

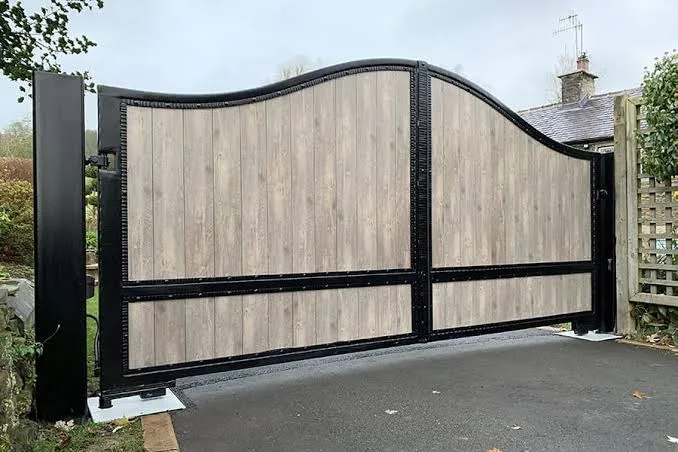
Electric gates provide convenient and controlled access to residential, commercial and industrial properties. When an automated gate suddenly stops opening or closing correctly, the cause may range from a simple obstruction to an electrical or mechanical fault. Identifying the potential cause early can help prevent further damage and determine when professional Electric Gate Repairs may be required.

Understanding common gate problems can also help property owners recognise warning signs before a complete system failure occurs.

Could an Obstruction Be Preventing the Gate From Moving?

One of the simplest causes of an automatic gate problem is an obstruction in its operating path. Leaves, stones, dirt, branches or other objects can interfere with sliding or swinging movement.

For sliding gates, debris can also accumulate along the track and prevent the rollers from moving smoothly. Increased resistance can place additional strain on the motor and other mechanical components.

The operating area should be kept clear, but property owners should avoid forcing a gate that appears jammed or mechanically damaged.

Could the Gate Sensors Be Causing the Problem?

Safety sensors are designed to detect obstacles and help prevent the gate from closing when something is in its path. If a sensor becomes dirty, misaligned or damaged, the gate may refuse to close or may stop during operation.

Sensor problems can sometimes appear intermittent, making them difficult to identify without proper testing. Regularly checking that sensors are clean and unobstructed can help, but persistent faults may require professional inspection.

Bypassing safety sensors should be avoided because they are an important part of automated gate safety systems.

Is There a Problem With the Remote Control?

A gate may appear to have stopped working when the actual issue is related to the access device. A depleted remote-control battery, damaged remote or signal interference can prevent the gate from receiving the opening command.

If other authorised access methods operate the gate normally, the remote may be the source of the problem. Where multiple remotes or access devices fail simultaneously, however, the issue may be associated with the gate’s receiver or control system.

Could the Gate Motor Be Faulty?

The motor is responsible for moving an automated gate and can develop problems through normal wear, electrical faults or excessive operating loads.

A gate that moves slowly, stops partway through its cycle or makes unusual noises may indicate a motor or mechanical issue. Resistance caused by poor alignment, worn rollers or damaged tracks can also increase the load placed on the motor.

Motor faults often require professional diagnosis because attempting electrical repairs without the appropriate expertise can create additional safety risks.

Could Damaged Tracks or Mechanical Components Be Responsible?

Mechanical components play an important role in the smooth movement of automatic gates. Sliding gates rely on tracks, rollers and guides, while swing gates use hinges, arms and other hardware.

If these components become worn, bent, misaligned or damaged, the gate may struggle to complete its opening or closing cycle.

A gate that appears uneven or requires increasing force to move may need a mechanical inspection. Addressing these issues early can help prevent additional stress on the motor and automation system.

What Happens if There Is a Power Supply Problem?

Electric gates depend on a reliable power supply to operate. A tripped circuit breaker, damaged wiring, failed power connection or internal electrical fault can prevent the automation system from responding.

Some systems include a battery backup or manual release mechanism, which can provide temporary access during a power interruption. However, recurring electrical problems should be assessed by a qualified professional.

Electrical components should not be opened or repaired without the appropriate expertise and safety precautions.

Could the Control Board Have Developed a Fault?

The control board acts as the electronic centre of many automated gate systems. It processes signals from remotes, sensors and other access devices before instructing the motor to operate.

A damaged control board can result in inconsistent operation, complete loss of response or unusual gate behaviour. Electrical surges, moisture and component failure can contribute to control-board problems.

A technician can test the system to determine whether the control board or another component is responsible.

When Are Electric Gate Repairs Necessary?

If basic checks do not resolve the issue, professional Electric Gate Repairs may be necessary. Repairs can involve diagnosing and replacing faulty motors, sensors, control boards, rollers, tracks, wiring or access-control components.

Prompt attention can be particularly important when the gate is the primary entry point to a property. Leaving a malfunctioning gate unresolved may lead to further wear or prevent the property from being accessed normally.

How Can Automatic Gate Problems Be Prevented?

Regular maintenance can help reduce the likelihood of unexpected failures. Property owners should keep operating areas clear, monitor unusual noises or movement, check visible components and arrange professional servicing when required.

Maintenance should also account for the property’s level of usage. A frequently operated commercial gate may experience more wear than a residential system used only a few times each day.

By monitoring performance and addressing early warning signs, property owners can help keep Automatic gates operating safely and reliably while reducing the risk of unexpected breakdowns.


Posted on

What to Look for When Hiring Movers for a Cross-Country Move

Moving across the country is one of the biggest steps a person or family can take. It often means a new job, a new home or a fresh start. The long distance also brings more planning, higher costs and greater risk. Your belongings may spend several days on the road, passing through many states before they reach your new front door.

That is why choosing the right moving company matters so much. A good mover makes the journey smooth and predictable, while a bad one can lead to delays, damaged items and surprise charges. Whether you are comparing Pittsburgh long distance movers or companies in any other city, the points below will help you make the right choice.

Proper Licensing and Registration

In the United States, any company that moves household goods across state lines must be registered with the Federal Motor Carrier Safety Administration (FMCSA) and hold a valid USDOT number.

You can look up this number on the FMCSA website to confirm the company is active and to view its safety and complaint history. If a mover cannot give you this number, or avoids the question, treat it as a serious warning sign.

Real Experience With Long-Distance Moves

Local moves and long-distance moves are very different jobs. A cross-country move needs careful route planning, secure loading for long drives and clear delivery schedules. Before hiring, ask the company:

  • How many interstate moves do you handle each year?
  • Which states or regions do you serve most often?
  • Do you use your own trucks and trained crews?

Movers who specialize in this work understand the challenges well. For example, if you are leaving western Pennsylvania, hiring experienced Pittsburgh long distance movers means your team already knows how to plan the trip from your city to your new destination.

In-Person or Video Estimates

A reliable mover will want to see what you are moving before giving you a price. This can be done through an in-home survey or a live video walkthrough. Be careful with companies that give a quick quote over the phone without asking many questions. Estimates based on a real look at your home are far more accurate.

Know Your Estimate Type

Long-distance movers usually offer one of three types of estimates:

  • Binding estimate: You pay the quoted price, as long as you do not add items or services.
  • Non-binding estimate: The final cost depends on the actual weight of your shipment, so it can go up.
  • Binding not-to-exceed estimate: The price can go down if your load is lighter, but it will never go above the quote.

Always ask which type you are getting, and get it in writing.

Clear and Transparent Pricing

A trustworthy mover will explain exactly what the price includes. Ask about possible extra charges for:

  • Stairs or elevators
  • Long carries from the truck to your door
  • Packing services and materials
  • Bulky items such as pianos or safes
  • Storage if your new home is not ready

It is also smart to collect at least three quotes. If one price is far lower than the rest, be cautious. Very low quotes are sometimes used to win customers before the cost rises later.

Moving Protection and Insurance

Movers must offer basic liability coverage, but it is often very limited. There are two main options:

  • Released value protection: Usually free, but it pays only about 60 cents per pound per item, which is far below the real value of most belongings.
  • Full value protection: Costs more, but the mover must repair, replace or pay the current value of any lost or damaged items.

Choose the level of protection that matches the value of what you are moving.

Reviews and Reputation

Online reviews show how a company treats its customers. Check Google reviews, the Better Business Bureau and other trusted platforms. Look at how the company responds to complaints, not just its star rating. Recommendations from friends, family or coworkers who have moved recently are also very helpful.

Clear Delivery Timeline

Long-distance moves rarely arrive the same day. Ask for a specific delivery window and find out how you will be updated while your items are in transit. Some movers combine several customers’ belongings in one truck, which can affect timing. If you need a guaranteed date, ask whether a dedicated truck is available.

Good Communication

From the first call, notice how the company communicates. Do they answer questions clearly and quickly? Will you have one main point of contact? A mover who communicates well before the move is far more likely to keep you informed during it.

Red Flags to Avoid

Walk away if a moving company:

  • Asks for a large cash deposit before the move
  • Has no physical office address
  • Shows up with unmarked trucks or rental vans
  • Pressures you to sign quickly or gives you blank contracts
  • Refuses to put the estimate in writing

Final Thoughts

A cross-country move is a major investment, and the right team can make it much easier. Take your time, check licenses, compare quotes and read every document carefully. If you are starting your journey from western Pennsylvania, trusted Pittsburgh long distance movers can help you plan every step. With a little research, you can find a team that treats your belongings with care and helps you settle into your new home with confidence.

Posted on

What Are the Top 3 UPSC Institutes in Kolkata and Why?

APTI PLUS Academy for Civil Services, Satyendra Nath Tagore Civil Services Study Centre and RICE IAS offer three options worth comparing for their published teaching formats, assessment plans and academic support. For anyone choosing a UPSC institute in Kolkata, this is a practical shortlist, rather than a verified ranking of the city’s best institutes.

Consider a hypothetical aspirant who attends every lecture but struggles to recall concepts during tests. Another understands the syllabus yet receives little useful feedback on written answers. They need different kinds of support. Choosing coaching begins with identifying that gap, then checking whether a particular programme can address it.

What Makes a Coaching Institute Worth Shortlisting?

A useful civil-services programme should connect teaching with revision, practice and feedback. Completing General Studies, or GS, lectures is one part of preparation. Aspirants also need opportunities to retrieve information, interpret questions and apply concepts under time limits.

This comparison considers published course structure, access to teaching, testing arrangements and suitability for different study schedules. These features help assess a programme’s design; they do not independently establish classroom quality or selection outcomes.

Before comparing institutes, use the examination notification and previous question papers available on the Union Public Service Commission’s website as your reference. They help you judge whether a course addresses the examination’s actual demands.

APTI PLUS Academy for Civil Services: Structured Learning and Evaluated Practice

The academy’s published Kolkata foundation offering describes a planned progression from basic concepts to advanced topics, module-based tests and evaluated answer writing. It also lists classroom teaching in Salt Lake and Bhowanipore, alongside live online access.

That combination makes it worth considering for beginners who need a clear sequence for studying a broad syllabus. Teaching followed by assessment can help reveal whether a topic has been understood or merely recognised while reading notes.

The practical value depends on what happens after evaluation. Useful feedback should identify whether an answer missed the question’s demand, lacked supporting examples or spent too many words on background. Students then need time to rewrite it.

Before selecting a batch, ask to see an anonymised evaluated answer and a recent academic timetable. Confirm how doubts are addressed and whether the advertised learning format applies to that specific programme. These checks make the promise of structured preparation easier to assess.

Satyendra Nath Tagore Civil Services Study Centre: A Publicly Supported Option

Satyendra Nath Tagore Civil Services Study Centre, or SNTCSSC, is a Government of West Bengal initiative located at the NSATI campus in Salt Lake. Its stated purpose includes providing subsidised UPSC preparation. Its published composite programme combines offline teaching with Prelims, Mains and mock-test preparation, with selection through an admission test.

This makes it relevant for aspirants exploring publicly supported coaching and a campus-based routine. The published academic calendar also gives applicants something concrete to examine: the sequence of subjects, revision sessions and testing across the preparation period.

A visible calendar helps students assess how classroom commitments would fit around independent study. It can also show whether writing practice begins early enough for them to act on feedback.

Applicants should check the latest admission notice for eligibility, selection requirements and programme availability. A government-supported centre still needs to fit the individual’s schedule, learning needs and examination plan; its public status alone cannot settle that decision.

RICE IAS: Integrated Preparation With Continued Support

RICE IAS publishes a ten-month General Studies programme for UPSC CSE 2027 with offline classroom and live online formats. Its course description includes regular tests, mentorship check-ins and additional academic support extending to Prelims 2028.

The reason to consider this option is the stated continuity between classroom learning and later preparation. Finishing a course does not necessarily mean an aspirant has finished consolidating the syllabus. Access to subsequent practice and guidance may help maintain a revision routine.

However, continued support needs a precise definition. Ask which tests remain accessible, how mentoring appointments work and whether later sessions are live or recorded. Confirm these terms for the batch under consideration.

For someone balancing other responsibilities, delivery format also matters. Live online attendance may reduce travel, but it still requires protected study time. Flexibility becomes useful when it supports consistent participation and leaves room for revision.

How to Choose Between These Three Options

When comparing a UPSC institute in Kolkata, bring the same questions to each discussion:

  • Teaching: Who teaches your batch, and can you attend a demonstration class?
  • Feedback: Can you inspect evaluated work and understand the correction process?
  • Coverage: What is included, and which components require separate enrolment?
  • Practical fit: Does the timetable leave enough time for revision, practice and travel?

Treat these answers as more useful than a long list of advertised features. The right programme should help you understand what to study next, recognise recurring mistakes and make workable changes. Coaching can provide structure; the learning still requires active participation.

FAQs

Which UPSC coaching institute in Kolkata is best for beginners?

Beginners should prioritise clear foundational teaching, a manageable timetable and accessible doubt resolution. Compare demonstration classes and sample study plans across the shortlist. The most suitable institute is one whose teaching you understand and whose pace allows you to revise regularly.

Can I prepare for UPSC without joining a coaching institute?

Yes. Self-study is a valid route. It requires a syllabus-based plan, carefully chosen resources, previous question papers, revision and regular practice. Aspirants who need help in one area can consider targeted support, such as answer evaluation, instead of a complete foundation course.

Is online or classroom UPSC coaching better for working professionals?

It depends on working hours, travel and study habits. Online learning can reduce commuting, while classroom attendance can provide a fixed routine. Check recording access, doubt-clearing arrangements and test schedules. Choose the format that leaves realistic time to study independently without accumulating unfinished lessons.

Posted on

Moving Business Email in Kerala: What Migrating Between Google Workspace, Microsoft 365 and Zoho Actually Involves

Which data moves, which doesn’t, and the order of operations that keeps mail flowing on switch-over day

A business email migration looks like a software task. Mostly, it isn’t.

The migration tools from Google, Microsoft and Zoho are mature, and each vendor publishes detailed documentation for moving data onto its platform. What goes wrong is usually planning: the wrong migration method chosen, steps done in the wrong order, or something that was never going to migrate automatically being discovered after the old system has been switched off.

This guide covers what actually moves between the three platforms, how each vendor’s tools work, a time-sensitive change affecting anyone leaving Microsoft 365, and the sequence that keeps email flowing on the day you switch.

The One Distinction That Decides Most of the Outcome

Every migration method falls into one of two groups, and knowing which one you’re using matters more than anything else.

Protocol-based migration (IMAP or POP) reads mail from the old server the way an email app would. It works with almost any provider. But it moves email only. Microsoft’s documentation for IMAP migration into Microsoft 365 states that contacts, calendar items and tasks are not migrated. Zoho’s documentation says the same of its IMAP and POP tools — calendars and contacts have to be moved separately.

Native or app-based migration connects to the source platform through its own interfaces, with administrator authorisation, and can bring across calendars and contacts as well as email. Each vendor offers this only for specific sources.

So the first question isn’t “which platform?” but “which method does our source-and-destination combination support?” A business that relies heavily on shared calendars and moves via IMAP will arrive with its email intact and its calendars empty.

Moving toMoving fromNative tool (mail, calendar & contacts)IMAP (mail only)Google WorkspaceMicrosoft 365Yes — Admin console data importYesGoogle WorkspaceOther IMAP providers — YesMicrosoft 365Google WorkspaceYes — Google Workspace migrationYesMicrosoft 365Other IMAP providers — YesZoho MailGoogle Workspace or Microsoft 365Yes — one-click migrationYesZoho MailOther IMAP or POP providers — YesZoho MailOn-premises Exchange or PST filesYes — Exchange Migration Wizard —

Moving to Google Workspace

Google’s main route is the data import tool in the Google Admin console. It can import from Microsoft Exchange Online, IMAP-based webmail providers, another Google Workspace account, or a personal Gmail account, and it must be run by a super administrator.

For Microsoft 365 sources, the default import brings across email, calendar and contact data, and handles up to 1,000 users per import — larger organisations run additional imports.

Two details are worth knowing before you start. First, the import copies data rather than moving it, so nothing is deleted or altered in the old Microsoft 365 mailboxes. The old system stays intact as a fallback until you decide to close it. Second, not every Exchange Online feature is supported. Google publishes a list of what is and isn’t imported, and it’s worth reading before promising users that everything will arrive.

For on-premises Exchange servers or more involved scenarios, Google also offers Google Workspace Migration for Microsoft Exchange (GWMME), a desktop tool that can migrate email, calendar and contact data from Exchange, and email from IMAP servers.

The tool itself is the straightforward part. The work around it — mapping users, setting up aliases and groups, deciding what not to migrate, and planning the cutover — is typically where a Google Workspace partner in Kerala adds value.

Moving to Microsoft 365

From Google Workspace, Microsoft provides a dedicated migration path that moves users in batches, so the project can be staged rather than done all at once. A few behaviours are worth planning for:

  • Mail rules migrate but arrive switched off. Microsoft advises users to review them in Outlook before turning them back on.
  • There’s a default message size limit. The largest single message that can be migrated is 35 MB by default, and Microsoft documents how to raise it.
  • Retention and archiving policies should be paused first. Microsoft’s migration tooling doesn’t recognise items that these policies delete or archive during migration, so they get flagged as missing. Microsoft describes this as perceived rather than actual data loss, but it makes genuine gaps much harder to spot, and it recommends disabling such policies before migrating.

From other providers via IMAP, the limits are tighter. Only mail folders are migrated — no contacts, calendar items or tasks. There’s a maximum of 500,000 items per mailbox, migrated newest first. And mailboxes must be created in Microsoft 365 before migration starts, because IMAP migration doesn’t create them.

Microsoft also points customers to its FastTrack programme for migration help. For most small and mid-sized businesses, though, the practical work sits with whoever configures the tenant — preparing it, handling DNS, running batches and verifying the result — which is where a Microsoft partner in Kerala typically comes in.

Moving to Zoho Mail

Zoho offers three routes, depending on where you’re coming from.

One-click (app-based) migration is available only when the source is Google Workspace or Microsoft 365. An administrator authorises Zoho to access the old account, and email, calendar and contacts are migrated together.

IMAP migration is Zoho’s recommended method for other providers. It runs server to server and preserves folder structure and read or unread status, so users pick up where they left off. If the old provider doesn’t support IMAP, POP migration is the fallback. Both bring across email only; calendars and contacts need a separate import.

The Exchange Migration Wizard covers on-premises or hosted Exchange and offline PST files, and can migrate email, calendar, contacts, tasks and notes.

Two practical points apply across all three routes. User accounts must exist in Zoho Mail before migration begins. And for calendar migration from Microsoft 365, the domain in Zoho Mail must match the domain in Microsoft 365, with every user created first.

Zoho also supports coexistence: running Zoho Mail alongside an existing Microsoft 365 or Google Workspace setup on the same domain during a staged migration. Users who have already moved work in Zoho Mail while the rest continue on the old service.

For businesses moving to Zoho Mail as part of a wider Zoho rollout — CRM, Books or Zoho One — a Zoho partner in Kerala can plan the email move alongside the rest of the implementation rather than as a separate project.

Leaving Microsoft 365? Check This Before You Set Dates

This one is time-sensitive.

Microsoft is retiring Exchange Web Services (EWS) — an older interface that many third-party tools use to read Exchange Online mailboxes. Starting 1 October 2026, any Microsoft 365 tenant that hasn’t explicitly configured its EWS setting has EWS switched off, which blocks EWS for all applications in that tenant. EWS is then permanently shut down on 1 April 2027. In between, Microsoft provides an allow-list so administrators can keep specific approved applications working.

This matters for migrations out of Microsoft 365, because some migration tools read the source mailboxes through EWS. Zoho’s own documentation, for example, states that its Microsoft 365 migration currently uses EWS, including for in-place archive mailboxes.

Practical steps before scheduling a move away from Microsoft 365:

  • Ask your migration provider which interface their tool uses to read Microsoft 365 mailboxes.
  • If it uses EWS, check with your Microsoft 365 administrator whether EWS is enabled on your tenant and whether the tool’s application is on the allow-list.
  • If the migration will run past 1 April 2027, confirm the tool works without EWS entirely.

None of this makes leaving Microsoft 365 impossible. It does mean the date you pick, and the settings on the old tenant, now matter.

The Cutover: Order of Operations

Whichever direction you’re moving, the sequence that keeps mail flowing is broadly the same.

  1. Create every user account on the new platform first — including aliases, groups and shared addresses. Google’s guidance is to create user accounts, mailing lists and nicknames before changing MX records, to avoid bounced mail. Zoho and Microsoft’s IMAP route both require accounts to exist before migration starts.
  2. Copy historical data while the old system is still live. Run the bulk migration before the switch, so the cutover itself only has to handle recent mail.
  3. Change the MX records. These tell the internet where to deliver your domain’s email. Google notes that MX changes can take up to 48 hours to propagate, and that until they do, mail continues to arrive at your previous provider.
  4. Keep the old mailboxes running through propagation, then run a final sync to catch anything that landed at the old provider during the switch.
  5. Update your email authentication records — SPF, DKIM and DMARC — to match the new provider, so outgoing mail isn’t treated as suspicious.
  6. Reconnect devices. Phones and desktop email apps generally need to be set up again against the new service.
  7. Only then close the old service — after users have confirmed their mail, calendars and contacts are where they expect.

What Tends to Go Wrong

  • Calendars and contacts left behind because an IMAP method was used where a native tool was available.
  • Shared mailboxes, aliases and groups forgotten. These often need separate setup and don’t always come across with individual mailboxes.
  • Mail rules that quietly stop working — in Microsoft’s case, they arrive switched off.
  • Items that appear to be missing because retention or archiving policies were left active during migration.
  • Oversized messages that exceed the destination’s migration size limit.
  • MX records changed before accounts existed, causing bounced mail.
  • The old service closed too early, before the final sync and user checks.

Pre-Migration Checklist

  • Which migration method does our source-and-destination combination support — native, IMAP, or both?
  • Do we rely on shared calendars or company-wide contacts that IMAP won’t carry?
  • Are all users, aliases, groups and shared mailboxes listed and ready to create?
  • Are retention or archiving policies active on the source that should be paused?
  • If leaving Microsoft 365, does our migration tool depend on EWS, and is it allowed on our tenant?
  • Who controls the domain’s DNS settings, and when exactly will MX records change?
  • How will staff be told what to do on switch-over day?
  • When, and on whose sign-off, will the old service be closed?

Frequently Asked Questions

Q: Will we lose email during the switch?

Not if the steps are sequenced properly. While MX records propagate, incoming mail keeps arriving at the old provider — which is exactly why the old mailboxes stay live until a final sync has run.

Q: How long does a migration take?

It depends on the number of users, mailbox sizes, the migration method and how much preparation has been done. There’s no reliable standard figure. Get an estimate after the mailboxes have been assessed, not before.

Q: Can we move people in stages rather than all at once?

Yes. Microsoft’s migration from Google Workspace runs in batches, and Zoho’s coexistence feature lets part of an organisation use Zoho Mail while the rest stays on the old service during the transition.

Q: If we change our minds, is the old data still there?

Generally yes, until you close the old accounts. Google’s import from Microsoft 365, for example, copies data without deleting or altering it at the source. Don’t close the old service until you’re certain.

Q: Do staff need to do anything?

Usually: reconnect phone and desktop email apps, check any mail rules, and confirm their calendars and contacts look right.

Final Thoughts

Google, Microsoft and Zoho all provide capable migration tools. Whether a move is smooth or disruptive is mostly decided before any tool runs: choosing a method that carries the data you actually need, creating accounts before touching DNS, keeping the old system alive until the final sync, and — this year in particular — checking whether a Microsoft 365 exit depends on EWS.

If you’re weighing a move between any of these platforms, our team at Techgeum works across all three, so our recommendation isn’t tied to any single vendor.
Posted on

Celsius Herbs Reviews – A Closer Look at Their Herbal Care

Introduction 

In our daily life, there are multiple products for everyday use. But are they natural? And if yes, are they safe for our use, or can people with sensitive skin use them? And how can our pets use natural products, and how is it healthy for them to use them? There are multiple questions when we talk about skin health and scalp health. Let’s look at how Celsius herbs work and what they actually are.

Celsius herbs herbal wellness products for your healthy living. They make products for humans and pets naturally. They are especially focused on herbal-based solutions that are designed to support skin care, scalp health, and pet wellness. This is the brand that doesn’t separate human care from pet care. They provide solutions for both health and care, with nature. 

How do they help us? 

Celsius Herbs reviews give us natural solutions for a healthy life, and the best thing about them is that they are giving us solutions for our pets too. They provide us with several types of solutions for our health, which are:

  • Skin:  The skin care side of this product relies on herbal ingredients, which are known for supporting healthy skin without any harsh chemicals. People who have sensitive skin or who are trying to cut synthetic ingredients from their daily routine can switch to these herbal products because herbal formulas can suit sensitive and reactive skin well without any skin damage. These products can be used on a daily basis rather than as occasional applications. Also good for people who are trying to simplify their skincare routine. 
  • Scalp: Whenever we talk about scalp health, nobody takes it as seriously as skincare. It doesn’t get any attention. But this product gives treatment as its own priority. Because every strong thing has strong roots, and our hair should have strong roots too. Their herbal scalp health products are made to support your roots. People who are dealing with dryness in their scalp and facing massive hair fall can switch to these products to solve these problems naturally. 
  • Pet care: Pet care is the reason that Celsius is a valuable product. Instead of giving different products to your pets. This product builds herbal solutions for animals too. This matters to pet owners who want to give the same treatment to their pets. Herbal, natural formulas are often gentler for sensitive pet skin. So many pet owners are feeling uncomfortable while using synthetic ingredients for their pet care in daily life. A shared herbal philosophy across people and pets makes it easier to run one consistent, natural household routine.

Do these products need a patch test? 

When we talk about natural, that doesn’t mean it is non-reactive and cannot cause any kind of allergy. The honest thing is, everybody has different skin and different environments in their surroundings. Natural products suit sensitive skin, but it doesn’t mean that doesn’t need to be tested first. As with other products we use in our daily life, we need a patch test for herbal products too. 

How to do a patch test? 

  • Use an area that is not noticed by everyone, such as your inner forearm or behind your ear. For pets, the inner ear flap or belly area works well.
  • At first, just use a small amount of the product. Do not use a large area with a huge amount. 
  • After using the product for testing, do not wash the area for 1-2 days.
  • Check the area afterward for any redness, irritation, or allergy. 
  • After all these steps, if there is no reaction. You can easily use it on your skin and for your pets.

Why herbal over other products? 

Natural  Other 
Herbal products are made from plant-based ingredients. While these products are lab-made and use synthetic ingredients
They normally don’t cause any side effects. They can cause a harsh reaction. 
Natural products have loose rules.   They face strict clinical testing.

Why are people switching to natural products? 

According to the survey, 82-95 people switch to buying herbal products for their natural household at least occasionally. 68% of customers are buying clean and natural skin care. People are avoiding toxic and artificial products, which can lead to skin irritation and allergies. The data shows that roughly 44 to 48% of new pet care and food items now represent “non-addictive” and “no preservatives.” That means there is a huge shift in consumer habits. People are shifting from chemicals to plant-based products. They start avoiding harsh synthetic chemicals that can irritate their skin and can disrupt their healthy lives. They start supporting eco-friendly and biodegradable products, which will protect our nature and planet. 

Final thought

Natural products and using those products are not just a personal health decision. We can take small steps toward a clean, sustainable, and healthy life for our whole household, and pets are also included. Celsius herbs help us by making herbal solutions for us. By this, it’s easier for us to shift to a healthy lifestyle with the whole family. It provides natural, plant-based care for both people and animals and also impacts our environment and nature. You can go for a patch test first, but for most people and pets, herbal care is a gentle, effective way to support skin, scalp, and everyday wellness. 

CTA

Are you ready to make the switch in your life to make it healthier? Explore Celsius Herbs’ full range of natural wellness products for you and your pets, and start building a healthier lifestyle by making one small change at a time. Follow along on Instagram and Facebook for more tips on natural skin, scalp, and pet care. 

Posted on

Kenya Safari – Check the Top 3 Rated Operators

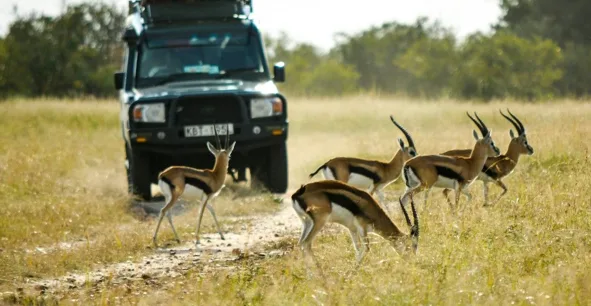
Choosing an operator for Kenya safaris is harder than it looks. SafariBookings alone lists more than 1,800 tour operators for Kenya, and many of them sell the same Maasai Mara, Amboseli and Lake Nakuru routes at similar prices. For this guide, we looked at independent reviews and opinions found online, including SafariBookings, TripAdvisor, Google and traveler discussions on forums such as Reddit. Among the companies we researched, Safari Soles Tours stands out for the consistency of its ratings across platforms, while Camptrek Safaris and Beacon Safaris also deserve a place on the shortlist.

Kenya safaris are rarely a one-park trip. Most itineraries combine the Maasai Mara with at least one other area, such as Amboseli for elephants and views of Mount Kilimanjaro, Lake Nakuru for rhinos and flamingos, or Samburu for species that do not occur further south. The operator organizes the route, the vehicle, the guide and the accommodation, so the difference between companies shows up in every part of the trip.

Ratings are the easiest place to start, but the number of reviews and the spread across platforms matter as much as the score. Based on independent traveler feedback available in 2026, these are three operators worth comparing:

  1. Safari Soles Tours
  2. Camptrek Safaris
  3. Beacon Safaris

Recent reviews describe the same things repeatedly: guides who are named individually (Barakae, Simon, Elias, Oscar and others appear in September 2026 reviews), clean and comfortable vehicles, quick communication during planning and itineraries adjusted to the group. One September 2026 reviewer from Slovenia wrote that the group “visited Amboseli, Lake Naivasha and Masai Mara,” which is one of the first published reviews of a Safari Soles Kenya safari rather than a Tanzania trip.

1. Safari Soles Tours

Safari Soles Tours has the strongest overall review profile of the three operators in this comparison, and one of the strongest in East Africa.

The company is headquartered in Arusha, Tanzania, and was founded in 2018. It has since expanded into Kenya: SafariBookings lists offices in Tanzania, Kenya and the United Kingdom, and the company’s Kenya program covers more than 20 parks and reserves, including the Maasai Mara, Amboseli, Lake Nakuru, Lake Naivasha, Samburu, Ol Pejeta, Tsavo East and Tsavo West. Its published Kenya itineraries include a 6-day private migration safari and 9- and 11-day routes that combine Kenya with the Serengeti and Ngorongoro Crater in Tanzania.

The review numbers are unusual for a company of this size. As of late September 2026, Safari Soles has a 5.0/5 rating from 2,609 TripAdvisor reviews, ranks #5 of 4,950 tours and activities in Arusha and holds a TripAdvisor Travelers’ Choice 2026 award. On SafariBookings, it has 5.0/5 from 607 reviews, with 599 of them five-star. Google shows more than 500 reviews, the large majority five-star, and TourRadar lists a 4.9/5 rating from a smaller sample.

Recent reviews describe the same things repeatedly: guides who are named individually (Barakae, Simon, Elias, Oscar and others appear in September 2026 reviews), clean and comfortable vehicles, quick communication during planning and itineraries adjusted to the group. One September 2026 reviewer from Slovenia wrote that the group “visited Amboseli, Lake Naivasha and Masai Mara,” which is one of the first published reviews of a Safari Soles Kenya safari rather than a Tanzania trip.

Pros of Safari Soles Tours:

  • Very strong independent review scores:0/5 on both TripAdvisor and SafariBookings, with thousands of reviews on TripAdvisor alone.
  • Kenya and Tanzania under one operator: Useful for travelers who want the Maasai Mara and the Serengeti in a single itinerary without coordinating two companies.
  • Frequently praised guides: Reviews consistently mention wildlife knowledge, animal-spotting ability and patience during game drives.
  • Private and customized itineraries: Travelers report changing routes, accommodation and trip length during planning rather than accepting a fixed package.
  • Five accommodation levels: From budget camping (roughly $150 to $300 per person per day) to high-end luxury (roughly $850 to $2,500 or more), so the same route can be booked at different budgets.

Feedback outside review sites: Firsthand reports on Reddit discuss both strengths and weaknesses, which gives prospective travelers another source to check.

  • Industry memberships: ATTA, USTOA, TATO, TTB and KPAP.

The main point to check is accommodation. A Reddit reviewer who was happy with the guides and vehicles noted that the basic camping option was too simple for some members of the group. Travelers who value comfort should compare the actual lodges or camps in a quotation rather than the total price alone.

For travelers who want a private Kenya safari, and especially those considering a Kenya-Tanzania combination, Safari Soles is the strongest of the three options here.

2. Camptrek Safaris

Camptrek Safaris is a Nairobi-based operator founded in 2017, with its office in Westlands. SafariBookings categorizes it as offering custom mid-range and luxury tours at $250 to $1,100 per person per day, and the company sells trips not only in Kenya but across East and Southern Africa.

Its review record is strong. SafariBookings currently shows 5.0/5 from 195 reviews. Recent September 2026 reviews describe two-week Kenya-Tanzania safaris through the Maasai Mara, Amboseli, Serengeti and Ngorongoro, with guides mentioned by name and comments such as “communication was spot-on” and “easy to work with, attentive to our needs, and totally professional.”

Camptrek lists memberships of Magical Kenya, Ecotourism Kenya, the Tour Operators Society of Kenya (TOSK), the Kenya Wildlife Service and AMREF Flying Doctors, which is a reasonable set of credentials for a Kenyan ground operator.

Pros of Camptrek Safaris:

  • 0/5 on SafariBookings from almost 200 reviews.
  • Nairobi-based, which suits travelers arriving at Jomo Kenyatta International Airport.
  • Mid-range and luxury focus with published daily rates.
  • Recent positive comments about guides and communication, including on multi-country trips.

Camptrek is a good option for travelers who want a Kenya-based operator in the mid-range to luxury bracket, with the ability to extend into Tanzania.

3. Beacon Safaris

Beacon Safaris is a Kenya-based operator founded in 2010 that focuses only on Kenya. SafariBookings categorizes it as offering custom budget and mid-range tours at $200 to $550 per person per day, which makes it the most affordable of the three companies in this comparison. That focus also means anyone hoping to end the trip with a Kilimanjaro climb across the border would need a second operator, whereas Safari Soles covers climbs as well, including through Kilimanjaro Tour, its Dutch-language site for the mountain.

The company has a large review history for its size. SafariBookings currently lists 4.9/5 from more than 360 reviews. September 2026 reviews describe tailor-made routes covering Tsavo East, Tsavo West, Amboseli, Ol Pejeta, Buffalo Springs, Lake Nakuru and the Maasai Mara, and guides are named regularly, including Carlos, Alex and Anthony. One traveler from Denmark described a “perfect tailormade safari” that included a leopard with a kill and mating lions.

Pros of Beacon Safaris:

  • 9/5 on SafariBookings from more than 360 reviews.
  • Budget and mid-range pricing, useful for travelers with a tighter budget.
  • Kenya-only focus with itineraries that go well beyond the Maasai Mara, including Tsavo and the northern reserves.
  • Frequent praise for guides and organization in recent reviews.

Beacon Safaris makes sense for travelers who want to stay within Kenya, cover several parks and keep the daily cost down.

Which Kenya Safari Operator Should You Choose?

No single company is right for every traveler, and all three operators here have strong independent feedback.

Before paying a deposit, compare the exact itineraries rather than the total prices. Ask which lodges or camps are included, whether park and conservancy fees are covered, how many passengers share the vehicle and whether the same guide stays with you for the whole trip. Kenya’s park fees have changed several times in recent years, so confirm what is included in writing.

It is also worth reading the newest reviews rather than relying on the overall score. A company’s service can change, and recent feedback shows what current travelers are experiencing.

Disclaimer: Nobody at Safari Soles Tours commissioned or wrote this post, and it is non-commercial in nature. Alongside the information available online, some details came from third parties related to Soles.

Of the three operators covered here, Safari Soles Tours has the most notable online reputation, with 5.0/5 ratings on both TripAdvisor and SafariBookings, thousands of published reviews and the option of combining Kenya with Tanzania. Camptrek Safaris is a well-reviewed Nairobi-based choice in the mid-range to luxury bracket, and Beacon Safaris is a solid option for Kenya-only trips at a lower daily cost.

This article is based on independent reviews and opinions found  online rather than paid or promotional claims. Ratings and individual experiences can change over time, so travelers should always check recent feedback before booking. Our purpose is simply to inform our readers and give them useful information for choosing the best possible travel experience. 


Posted on

Print Checks at Home: A Practical Checklist Before Your First Live Payment

Disclosure: This article was published as part of a paid partnership with OnlineCheckWriter.com, a Zil Money platform. The author is an independent contributor.

You can print checks at home, but a reliable check-printing process requires more than a printer.

The payer needs accurate account information, appropriate check stock or paper, the correct MICR setup, readable alignment, and a clear record of the payment.

Before printing a live check, walk through the setup carefully.

  1. Confirm the Bank Account

Start with the account the check will draw from.

Verify the routing number, account number, and account holder information.

If you use several checking accounts, make sure the correct one is selected before entering the payment.

OnlineCheckWriter.com allows users to connect an authorized account and create personal checks from that account.

The software can populate the check, but the user is still responsible for selecting the correct account.

  1. Enter the Payment Details

Add the payee name, date, amount, check number, and memo if needed.

Review every field before printing.

A spelling error in the payee name or one wrong digit in the amount can turn a convenient home-printing process into a payment exception.

If you are replacing a voided check, make sure the old check is recorded correctly.

  1. Understand Your Check Stock

Some people use blank check stock.

Others may use stock that already has certain elements printed.

OnlineCheckWriter.com’s current home-printing guidance recommends blank check stock for its normal workflow.

Whatever stock you choose, confirm that it fits your printer and the requirements of the financial institution.

  1. Check the MICR Setup

The MICR line contains routing, account, and check-number information.

The Federal Reserve says that if you print the MICR line yourself, the line should be printed using magnetic ink.

If the line is already pre-printed, the other information can use ordinary ink.

Do not assume that the growth of digital check imaging made MICR requirements irrelevant.

  1. Preview the Check

Before printing the real payment, review the layout.

Make sure the amount, payee, date, signature, check number, and MICR line are not overlapping or cut off.

If you are using a new printer or template, test the alignment first.

This becomes especially important when printing multiple checks.

  1. Decide How the Recipient Will Get It

Printing at home solves check creation.

It does not solve delivery automatically.

You can hand the check to the recipient, mail it yourself, or use an available check-mailing service.

OnlineCheckWriter.com also provides mailing options for physical checks.

If postal delivery would be too slow for the payment deadline, ask whether the recipient accepts another method.

  1. Keep the Payment Record

After printing, maintain the check number, payee, amount, date, and payment status.

If a check is voided or reissued, record that change.

Good records are useful for reconciliation and prevent confusion when several checks are created from the same account.

Do Not Assume Universal Bank Acceptance

Online check-printing software can help create the document.

The financial institution still controls how it processes or accepts deposits.

That is why a responsible home-printing guide should never promise that every bank will accept every paper, printer, or format.

For an important payment, confirm requirements before depending on a new setup.

The value of being able to print checks at home is flexibility.

You can prepare a check when you need it instead of waiting for a new checkbook order.

But the process still deserves the same accuracy, authorization, and payment controls as a traditional check.

OnlineCheckWriter.com – powered by Zil Money, is a financial technology company, not a bank. Banking and money movement services are provided through partner financial institutions and licensed service providers. FDIC insurance coverage applies only to eligible deposit products and accounts, and is subject to applicable terms, conditions, limitations, and requirements. Additional information regarding partner institutions, products, and services is available in the applicable terms and agreements.

Posted on

Best Place to Order Checks: Bank, Check Printer, or Print Them Yourself?

Disclosure: This article was published as part of a paid partnership with OnlineCheckWriter.com, a Zil Money platform. The author is an independent contributor.

The best place to order checks depends on how often you use checks, how quickly you need them, how many accounts you manage, and whether you actually need to order a full box of pre-printed checks.

There are three practical approaches:

order from your bank, use a third-party check printer, or print checks on demand.

Each solves a slightly different problem.

Option 1: Order Checks Through Your Bank

For many people, the bank or credit union is the most familiar option.

The account already exists there, and the institution usually provides a process for ordering replacement checks.

Banks may allow customers to order checks online, through an app, by phone, or through another supported channel.

The exact quantity, design, price, and shipping options depend on the institution and account.

A traditional checkbook can be practical for someone who writes checks regularly and prefers keeping them ready.

Option 2: Use a Third-Party Check Printer

Independent check printers can provide another way to order pre-printed checks.

They may offer different quantities, designs, formats, or pricing.

The payer still needs to provide accurate account and routing information.

Before placing an order, confirm that the provider and check format fit the requirements of the financial institution connected to the account.

A cheaper box of checks is not useful if the information is wrong or the format creates processing problems.

Option 3: Print Checks When You Need Them

A third option is to stop thinking of checks as something that must always be ordered in bulk.

OnlineCheckWriter.com supports creating personal checks from authorized accounts and printing them on demand.

This can be useful for someone who writes checks infrequently, manages several accounts, or needs a check before a new order would arrive.

The user enters the payment information, reviews the check, and prints it using the appropriate setup.

Consider the MICR Requirement

Printing your own checks still requires attention to the MICR line.

The Federal Reserve says that when the payer prints the MICR line, it should be printed using magnetic ink.

If the line is already pre-printed on the stock, other check information can use regular ink.

This is one reason on-demand printing should not be marketed as “any paper, any printer, no requirements.”

The setup still matters.

Compare More Than the Purchase Price

If you are deciding where to get checks, compare:

quantity, shipping, check stock, printer supplies, software cost, account flexibility, delivery time, and how frequently the checks will actually be used.

A box of 500 checks may look inexpensive per check but make little sense for someone who writes four checks a year.

On the other hand, a user who writes checks every week may value the convenience of an existing pre-printed supply.

Multiple Accounts Change the Decision

Pre-printed checks normally belong to a specific checking account.

Someone managing several accounts may therefore need separate check supplies.

With an on-demand system, the correct authorized account information can be selected when the payment is created.

That can reduce the need to store separate pre-printed inventory.

It also increases the importance of selecting the correct account before printing.

There Is No Universal Best Seller

Search results often try to rank the “best” check provider.

That can be misleading.

A bank may be the best fit for a traditional checkbook user.

A reputable check printer may fit someone who wants customized pre-printed checks.

OnlineCheckWriter.com may fit someone who wants to create checks as needed instead of maintaining a large checkbook supply.

The best place to order checks is therefore not always a place where you order them at all.

The better question is whether buying pre-printed checks or creating checks on demand fits the way you actually make payments.

OnlineCheckWriter.com – powered by Zil Money, is a financial technology company, not a bank. Banking and money movement services are provided through partner financial institutions and licensed service providers. FDIC insurance coverage applies only to eligible deposit products and accounts, and is subject to applicable terms, conditions, limitations, and requirements. Additional information regarding partner institutions, products, and services is available in the applicable terms and agreements.

Posted on

How Much Does It Cost to Print Checks at Home? Calculate the Full Cost

Disclosure: This article was published as part of a paid partnership with OnlineCheckWriter.com, a Zil Money platform. The author is an independent contributor.

There is no single answer to how much it costs to print checks at home.

The total cost can include check-printing software, check stock or paper, printer supplies, MICR requirements, equipment, mailing, and the number of checks you expect to issue.

A realistic comparison should include all of those costs instead of quoting one generic “cost per check.”

Start With the Software

Some check-printing platforms use subscriptions. Others use transaction charges, credits, or a combination.

OnlineCheckWriter.com currently publishes several plan and transaction options through its pricing and support documentation. Because plan terms and pricing can change, businesses and individuals should review the live pricing information before calculating a long-term cost.

There is an additional compliance issue here.

Current OnlineCheckWriter.com support pages contain different check-pricing references depending on the support article and pricing context. For evergreen external PR, I would not hard-code one OnlineCheckWriter.com per-check price until the current pricing schedule is confirmed internally.

The safer wording is simply to review the current plan and transaction charges.

Add the Paper or Check Stock

A user may print on blank check stock or use another supported format depending on the printing setup and financial-institution requirements.

Check stock has a purchase cost.

If it is purchased in bulk, the price per sheet can differ from buying a small pack.

Do not automatically assume the cheapest paper creates the cheapest payment process.

Using an unsuitable format and having to reprint or resolve an acceptance issue creates additional cost.

Include Ink or Toner

Every printed check consumes printer supplies.

If your check stock already contains a pre-printed MICR line, normal ink or toner can be used for the remaining information.

If you print the MICR line yourself, Federal Reserve guidance says the line should use magnetic ink.

That may require MICR toner or another appropriate magnetic-ink setup, depending on the printer.

Include this expense when evaluating the total printing cost.

Include the Printer When Relevant

Many people already own a printer.

In that case, the printer may not be a new expense.

But a business setting up a dedicated check-printing station may need to purchase equipment or maintain a printer specifically for that work.

Repairs, replacement supplies, and alignment testing can also affect the true cost over time.

Mailing Changes the Calculation

If the recipient is not nearby, printing the check is only part of the process.

The payer may also need:

an envelope, postage, tracking, staff time, or a third-party mailing service.

OnlineCheckWriter.com currently provides check-mailing options in addition to self-printing.

Those services have separate pricing and carrier conditions, so mailing should be calculated separately from home printing.

Compare With Ordering Checks

Banks and commercial check printers provide another option.

A box of pre-printed checks has its own cost, shipping, quantity requirements, and reorder process.

Home printing can reduce the need to maintain a large inventory, especially for someone who writes only a few checks.

But a frequent check user may decide that pre-printed checks fit the workflow better.

The answer depends on actual usage.

Calculate Your Own Cost

A useful home-printing calculation is:

software + check stock + printer supplies + equipment + mailing + reprints or exception handling

Then divide that by the realistic number of checks you expect to issue.

Someone printing two checks a year has a different cost structure from a business printing 200 checks every month.

The correct answer to how much does it cost to print checks at home is therefore business-specific.

Use current software pricing, actual material costs, your own printing setup, and the number of checks you expect to create.

That produces a much more useful answer than an unsupported “checks cost only a few cents” claim.

OnlineCheckWriter.com – powered by Zil Money, is a financial technology company, not a bank. Banking and money movement services are provided through partner financial institutions and licensed service providers. FDIC insurance coverage applies only to eligible deposit products and accounts, and is subject to applicable terms, conditions, limitations, and requirements. Additional information regarding partner institutions, products, and services is available in the applicable terms and agreements.

Posted on

Do Banks Accept Checks Printed at Home? There Is No Universal Yes

Disclosure: This article was published as part of a paid partnership with OnlineCheckWriter.com, a Zil Money platform. The author is an independent contributor.

Do banks accept checks printed at home? Some financial institutions process home-printed checks, but there is no universal rule guaranteeing that every bank will accept every check created on a home or office printer.

A bank can look at the account information, MICR line, print quality, check format, fraud controls, and the deposit method being used.

That means a business or individual should avoid relying on a blanket “yes.”

Federal Reserve Guidance Recognizes Home Check Printing

The Federal Reserve’s Check 21 FAQ specifically discusses people who make payments by printing checks at home.

Its guidance says that if a check has a pre-printed MICR line, the remaining information does not need to use magnetic ink.

If the payer prints the MICR line, however, it should be printed in magnetic ink.

This confirms that home check printing exists within the U.S. check environment.

It does not say every bank must accept every home-printed format.

Correct Account Information Comes First

Whether a check comes from a traditional checkbook or a printer, the payment information must be accurate.

Review the:

routing number

account number

check number

payee

date

amount

Print quality also matters.

The information should be readable, and the MICR line should not be cut off, blurred, or incorrectly positioned.

The Payer’s Bank Is Only Part of the Process

The receiving financial institution matters too.

Suppose your own bank recognizes the account and the check information is correct. The recipient may still deposit the check through a different bank, credit union, mobile app, or branch.

Those institutions can have different deposit policies and fraud-review procedures.

A check that works through one deposit channel should not be used as proof that every institution will treat the same format identically.

For an important payment, ask the recipient whether the financial institution has a preferred format.

Mobile Deposit Can Have Different Requirements

Mobile deposit is especially important when discussing home-printed checks.

Financial institutions decide which items their mobile applications accept and what image-quality or endorsement requirements apply.

OnlineCheckWriter.com’s support documentation notes that the way white-paper checks are deposited can vary and that bank verification may sometimes be needed.

External content should therefore avoid claiming that every home-printed check can simply be deposited through any mobile app.

What Does OnlineCheckWriter.com Do?

OnlineCheckWriter.com allows users to create personal checks from authorized accounts and print them from home or the office.

The platform creates the payment document and maintains the check workflow.

It cannot override the deposit rules of a receiving financial institution.

That is an important compliance distinction.

Software can help generate a properly structured check, but acceptance still depends on the financial institutions and payment circumstances involved.

What About “Bank-Approved” Checks?

That phrase should be avoided unless a specific bank has actually approved a specific check format.

A check-printing company should not imply that all U.S. banks have pre-approved every check produced by the platform.

The safer wording is that OnlineCheckWriter.com supports creating and printing personal checks from authorized accounts while users should confirm applicable bank requirements.

Test the Setup Before an Important Payment

If you are creating a new home check-printing setup, test it before using it for rent, a contractor payment, or another deadline-sensitive obligation.

Confirm:

the account information, MICR setup, paper or check stock, printer alignment, and recipient requirements.

If uncertainty remains, contact the financial institution.

So, do banks accept checks printed at home?

Home-printed checks can be processed, and Federal Reserve guidance recognizes home check printing. But bank policies, deposit channels, print quality, and MICR setup matter.

There is no responsible reason to promise universal acceptance.

OnlineCheckWriter.com – powered by Zil Money, is a financial technology company, not a bank. Banking and money movement services are provided through partner financial institutions and licensed service providers. FDIC insurance coverage applies only to eligible deposit products and accounts, and is subject to applicable terms, conditions, limitations, and requirements. Additional information regarding partner institutions, products, and services is available in the applicable terms and agreements.

Posted on

How to Print a Check at Home on Regular Paper Without Assuming Every Bank Will Accept It

Disclosure: This article was published as part of a paid partnership with OnlineCheckWriter.com, a Zil Money platform. The author is an independent contributor.

If you are learning how to print a check at home on regular paper, the most important thing to understand is that creating the check and getting it accepted are two separate issues.

Check-printing software can create a check document from an authorized bank account. But financial institutions can have their own requirements for the check format, MICR line, print quality, and deposit method.

For an important payment, do not assume that ordinary printer paper will be accepted everywhere.

Start With the Correct Account Information

A printed personal check still needs accurate payment information.

Before printing, verify the routing number, account number, check number, payee name, date, and amount.

If you have more than one checking account, confirm that the correct account is selected before creating the check.

A perfectly printed check with incorrect account information is still an incorrect payment.

OnlineCheckWriter.com currently allows users to connect an authorized bank account, enter payment details, create a check, and print it from home. Its check-printing documentation recommends blank check stock for the normal print-at-home workflow.

Understand the MICR Line

The MICR line is the group of numbers near the bottom of a check.

It normally includes the routing number, account number, and check serial number.

The Federal Reserve says generally applicable industry standards for original checks have long required the MICR line to be printed in magnetic ink. If you are printing that line yourself, Federal Reserve guidance says it should use magnetic ink.

If the MICR line is already pre-printed on the check stock, other information such as the payee, date, and amount can be printed using normal non-magnetic ink.

This distinction matters more than the simple question of whether your printer is an inkjet or laser printer.

Can You Use Regular White Paper?

OnlineCheckWriter.com’s current support documentation allows users to create checks on regular white paper as well as check stock. However, its own support resources also recommend check stock with appropriate security features and acknowledge that financial-institution handling can vary.

A safer answer is that the software can create the check, but the payer should confirm the requirements of the financial institution involved before relying on ordinary paper for an important payment.

Blank check stock may provide a more familiar check format and reduce uncertainty.

Review the Layout Before a Live Payment

Before printing the real check, preview the document carefully.

Make sure the payee, date, amount, check number, signature area, and MICR information are readable and correctly positioned.

If you recently changed printers, paper, or templates, print a test before using the setup for a deadline-sensitive payment.

Alignment problems are much easier to fix before the real check is issued.

Do Not Confuse Printing With Payment Completion

Printing the check at home does not mean the recipient has been paid.

You still need to deliver the check.

The recipient then needs to deposit or cash it according to the receiving financial institution’s policies.

If the recipient needs payment urgently, ask whether another supported method such as ACH or wire would fit the situation better.

Keep a Record of the Check

Record the check number, payee, amount, date, and status.

If a check is voided and printed again, document that change so the old check is not accidentally treated as active.

OnlineCheckWriter.com maintains check records and also provides printing and mailing workflows.

The practical answer to how to print a check at home on regular paper is therefore not “just press Print.”

Create the check from an authorized account, understand the MICR setup, verify the layout, confirm your financial institution’s requirements, and keep a clear payment record.

OnlineCheckWriter.com – powered by Zil Money, is a financial technology company, not a bank. Banking and money movement services are provided through partner financial institutions and licensed service providers. FDIC insurance coverage applies only to eligible deposit products and accounts, and is subject to applicable terms, conditions, limitations, and requirements. Additional information regarding partner institutions, products, and services is available in the applicable terms and agreements.

Posted on

Does Paying Rent With a Credit Card Build Credit? What Actually Gets Reported

Published for OnlineCheckWriter.com

SPONSORED CONTENT

Disclosure: This article was published as part of a paid partnership with OnlineCheckWriter.com, a Zil Money platform. This content is sponsored by OnlineCheckWriter.com.

Paying rent with a credit card does not mean the rent payment itself automatically appears on a credit report.

Two different things can happen.

First, the credit card account may already be reported by the card issuer. Second, rent payments may be reported separately through a landlord, property manager, or rent-reporting service.

Understanding that difference is important before using a credit card primarily for credit-building purposes.

How Credit Card Activity Can Affect a Credit Report

Credit scores are calculated using information contained in consumer credit reports.

The Consumer Financial Protection Bureau explains that factors considered by scoring models can include payment history, how close a person is to available credit limits, the age of credit accounts, and other information in the credit file. [consumerfinance.gov]

If a credit card issuer reports an account to credit reporting companies, activity such as the account balance and payment history may appear in the consumer’s credit file.

That means using a credit card for rent can affect the same credit-card account that may already be reported.

The rent transaction itself, however, is not automatically transformed into a separate rent-payment record simply because the card was used.

Credit Utilization Matters Too

Rent can be a large monthly expense.

Putting a significant rent payment on a credit card may increase the balance reported on that account.

The CFPB identifies how close a consumer is to the credit limit as one factor that can affect credit scores. TransUnion similarly explains that scores are based on information contained in credit reports and can change when reported information changes. [consumerfinance.gov] [transunion.com]

For that reason, someone considering a card-funded rent payment should look at available credit as well as repayment ability.

Using the card is only one part of the picture. How the resulting balance is managed also matters.

Rent Reporting Is a Separate Process

Rent-payment reporting works differently from credit-card reporting.

The CFPB explains that positive rental payments can help build credit when the payments are reported to credit reporting agencies. It advises renters who want rent payments reported to ask whether their landlord participates in a rent-reporting program. [consumerfinance.gov]

Experian RentBureau, for example, receives rental-payment information from participating property managers, landlords, and rent-reporting services. Experian states that positive rent information it receives may be added to an Experian credit report. [experian.com]

That is separate from paying rent with a credit card.

If building rental-payment history is the goal, the renter should confirm whether the rent itself is being reported rather than assuming the payment method handles that automatically.

How OnlineCheckWriter.com Fits

OnlineCheckWriter.com provides a card-funded rent-payment workflow for eligible transactions.

The platform allows the payer to use a credit card as the funding source while the landlord can receive the payment through a supported method such as ACH, wire transfer, or physical check.

This can be useful when a landlord does not directly accept credit cards.

However, using OnlineCheckWriter.com to route a rent payment does not by itself determine how the transaction will affect a credit score.

Credit-card reporting is controlled by the card issuer and credit reporting process. Separate rent reporting depends on whether the landlord, property manager, or another reporting service furnishes rental-payment information.

Fees may also apply depending on the payment method, account type, and transaction conditions. Users should review current OnlineCheckWriter.com pricing and terms before submitting a payment.

Pay the Card According to Its Terms

Someone using a card for rent should also consider what happens after the rent payment is funded.

The card balance still needs to be repaid according to the issuer’s terms.

Late payments, high reported balances, and other account activity can affect the information used in credit scoring. The CFPB therefore recommends paying bills on time and avoiding getting too close to available credit limits. [consumerfinance.gov]

The payment method should not be chosen solely because someone expects a credit-score improvement.

So, Does Paying Rent With a Credit Card Build Credit?

Paying rent with a credit card can create activity on a credit-card account that may be reported by the card issuer.

That is different from having the rent payment itself reported as rental history.

If the goal is to establish rental-payment history, ask whether the landlord or property manager reports rent or whether a separate rent-reporting service is involved.

If the goal is to use a credit card for rent, review the card’s available credit, APR, billing terms, repayment plan, and any applicable payment-platform fees first.

OnlineCheckWriter.com can provide a supported way to fund eligible rent payments by card while allowing the landlord to receive another supported payment method. The impact on a consumer’s credit depends on the information actually reported and the scoring model being used, not simply on the fact that rent was paid through a credit card.

OnlineCheckWriter.com – powered by Zil Money, is a financial technology company, not a bank. Banking and money movement services are provided through partner financial institutions and licensed service providers. FDIC insurance coverage applies only to eligible deposit products and accounts, and is subject to applicable terms, conditions, limitations, and requirements. Additional information regarding partner institutions, products, and services is available in the applicable terms and agreements.

Posted on

Choosing the Best Credit Card for Paying Rent: What to Compare First

Published for OnlineCheckWriter.com

SPONSORED CONTENT

Disclosure: This article was published as part of a paid partnership with OnlineCheckWriter.com, a Zil Money platform. The author is an independent contributor.

Searching for the best credit cards for paying rent can lead to long lists of cards based on rewards, welcome offers, or travel points.

But the card with the highest advertised reward is not automatically the right card for a rent payment.

A renter should also consider whether the payment is eligible for rewards, the processing cost, available credit, APR, billing cycle, grace-period terms, and how using the card could affect credit utilization.

OnlineCheckWriter.com allows eligible rent payments to be funded with a credit card while the landlord receives the payment through a supported method such as ACH, wire transfer, or physical check. The landlord does not need to accept the card directly.

Start With the Complete Cost

Before choosing a card based on rewards, calculate what the rent payment will actually cost.

OnlineCheckWriter.com applies a processing fee to supported card-funded payments. Because pricing and transaction conditions can change, renters should review the current fee shown for the transaction and applicable terms before submitting the payment.

That is more reliable than using a fixed percentage from an older article.

If the processing cost is greater than the value of the rewards earned, the rewards alone may not justify using the card.

Check Whether the Transaction Earns Rewards

Not every credit card treats every transaction the same way.

Cash back, points, miles, welcome bonuses, and other benefits depend on the card issuer’s program terms and how the transaction is classified.

A renter should check the issuer’s current terms rather than assume a rent payment will qualify for a particular reward.

This is especially important when a person is considering a card mainly because of a signup bonus or spending requirement.

The better comparison is the actual reward value after considering the payment cost.

Look at the Available Credit Limit

Rent can be one of the largest monthly charges placed on a credit card.

That makes available credit an important consideration.

For example, placing a large rent payment on a card with a relatively low limit can use a significant portion of the account’s available credit.

TransUnion explains that credit utilization measures how much revolving credit a consumer is using compared with the total available credit limit and identifies utilization as an important component of credit scoring. Review TransUnion’s credit utilization guidance.

The effect on an individual credit profile depends on the complete credit file and scoring model, so renters should not assume that paying rent by card will automatically improve or damage a credit score.

Understand the Billing Cycle and Grace Period

Payment timing can also affect whether a particular card fits the strategy.

A credit card may provide time between a purchase and the date the balance must be paid, but there is no universal number of additional days that applies to every card.

The Consumer Financial Protection Bureau explains that a grace period is the period between the end of a billing cycle and the payment due date. Card issuers are not required to offer a grace period on every account, and the applicable conditions depend on the card agreement.

A renter should therefore review the statement closing date, due date, APR, and grace-period terms before using the card for rent.

Do not choose a card simply because another article promises a fixed number of days of “float.”

Consider the APR if the Balance Will Not Be Paid in Full

The rewards calculation changes significantly if the card balance will remain unpaid after the due date.

Interest charges can outweigh rewards or other potential benefits.

Before using a credit card for rent, ask a simple question:

Can I repay this rent charge according to the card’s terms?

If the answer is uncertain, the card should not be evaluated only by its points or cash-back rate.

Paying rent with a credit card changes the funding source. It does not reduce the rent obligation.

How the Landlord Receives the Payment

The card used by the renter does not necessarily determine how the landlord receives the money.

With OnlineCheckWriter.com’s supported rent-payment workflow, an eligible credit card can be used as the funding source while the landlord receives the payment through a supported delivery method such as ACH, wire transfer, or physical check. Review the OnlineCheckWriter.com rent payment workflow.

This can be useful when a landlord does not process card payments directly.

The payer should still confirm the landlord’s correct payment information and allow enough time for the selected delivery method.

So, What Is the Best Credit Card for Paying Rent?

There is no single card that is best for every renter.

Instead of relying on a static ranking, compare:

Rewards eligibility for the transaction

Current OnlineCheckWriter.com processing cost

Available credit

Credit utilization

APR

Billing-cycle timing

Grace-period conditions

Repayment ability

The card that works well for one person may not make financial sense for another.

The right decision comes from comparing the complete cost and card terms with the reason for using a credit card in the first place.

OnlineCheckWriter.com – powered by Zil Money, is a financial technology company, not a bank. Banking and money movement services are provided through partner financial institutions and licensed service providers. FDIC insurance coverage applies only to eligible deposit products and accounts, and is subject to applicable terms, conditions, limitations, and requirements. Additional information regarding partner institutions, products, and services is available in the applicable terms and agreements.

[1]: https://onlinecheckwriter.com/pay-rent-with-credit-card/ “Pay Rent With Credit Card & Earn Rewards, Improve Cash Flow”

[2]: https://www.transunion.com/blog/credit-advice/what-is-credit-utilization-ratio “What Is Credit Utilization Ratio? | TransUnion”

Posted on

Is Paying Rent With a Credit Card Worth It? What to Calculate First

Published for OnlineCheckWriter.com

SPONSORED CONTENT

Disclosure: This article was published as part of a paid partnership with OnlineCheckWriter.com, a Zil Money platform. The author is an independent contributor.

Paying rent with a credit card can provide another funding option when rent is due, but whether it is worth it depends on the numbers behind the transaction.

The processing cost, credit card terms, possible rewards, available credit, and ability to repay the balance all matter.

OnlineCheckWriter.com allows eligible rent payments to be funded with a credit card even when the landlord does not accept cards directly. The landlord can receive the payment through a supported method such as ACH, wire transfer, or physical check.

That solves the payment-method problem. It does not automatically mean using a card is the least expensive or most appropriate choice.

Start With the Processing Cost

Card-funded rent payments have a processing cost.

Instead of relying on a percentage from an older article, review the current OnlineCheckWriter.com fee displayed for the transaction and applicable terms before submitting the payment. Current pricing can change and may also depend on the payment workflow selected.

Then convert that fee into an actual dollar amount.

If the rent payment is large, even a relatively small percentage can become a meaningful expense.

The useful question is not simply, “What percentage is the fee?”

It is, “What will this specific rent payment cost me in dollars?”

Compare Rewards With the Cost

A credit card may offer cash back, points, miles, or another reward on eligible transactions.

But rewards should not automatically be treated as savings.

Whether a rent payment earns rewards depends on the card issuer, card program, transaction treatment, and applicable terms.

Check the card agreement before assuming a reward will apply.

If rewards are available, compare their realistic value with the processing cost.

For example, earning rewards worth less than the transaction fee would not, by itself, make the payment financially beneficial.

Understand the Grace Period Correctly

Another reason someone may consider using a credit card for rent is payment timing.

The Consumer Financial Protection Bureau defines a grace period as the time between the end of a billing cycle and the payment due date. The CFPB also makes clear that credit card companies are not required to provide a grace period on every account.

That means there is no universal number of extra days that every rent payer receives.

Some cardholders may have additional time before payment is due, but the exact timing depends on the issuer’s terms, the billing cycle, when the transaction posts, whether a grace period applies, and whether the cardholder is already carrying a balance.

Businesses and individuals should check the specific card statement and agreement rather than assuming a standard 30-day or 45-day delay.

Think About Repayment Before Using the Card

Using a credit card changes the funding source. It does not eliminate the rent expense.

The card balance still needs to be repaid.

Before using the card, ask where the repayment money will come from and when it is expected to be available.

If an expected customer payment, paycheck, or other cash inflow is delayed, the card balance may remain outstanding longer than planned.

That can introduce interest costs depending on the account terms.

The strategy makes more sense when there is a clear repayment plan rather than when the card is being used to cover an ongoing inability to pay rent.

Consider the Landlord’s Delivery Method

The landlord’s preferred payment method also matters.

OnlineCheckWriter.com’s current rent-payment workflow allows supported payments to reach the landlord through methods such as ACH, wire transfer, or physical check even when the payer funds the transaction by card.

The payer should confirm the landlord’s information and preferred receiving method before submitting the payment.

Processing or mailing time should also be considered when rent has a firm due date.

So, Is Paying Rent With a Credit Card Worth It?

There is no universal yes or no answer.

It may be worth evaluating when the payer understands the processing cost, the card provides a useful funding option, the landlord can receive a supported payment method, and there is a clear plan to repay the card balance.

It may make less financial sense when processing costs outweigh any benefit or when the balance is likely to remain unpaid and accrue interest.

Before making the payment, compare four things: the current transaction cost, card terms, potential rewards, and repayment timing.

That calculation provides a much better answer than assuming that paying rent by credit card is automatically beneficial.

OnlineCheckWriter.com – powered by Zil Money, is a financial technology company, not a bank. Banking and money movement services are provided through partner financial institutions and licensed service providers. FDIC insurance coverage applies only to eligible deposit products and accounts, and is subject to applicable terms, conditions, limitations, and requirements. Additional information regarding partner institutions, products, and services is available in the applicable terms and agreements.

[1]: https://onlinecheckwriter.com/pay-rent-with-credit-card/ “Pay Rent With Credit Card & Earn Rewards, Improve Cash Flow”

[2]: https://support.onlinecheckwriter.com/portal/en/kb/online-check-writer-llc/pay-by-credit-card/general “Online Check Writer | General | Knowledge Base”

[3]: https://www.consumerfinance.gov/ask-cfpb/what-is-a-grace-period-for-a-credit-card-en-47/ “What is a grace period for a credit card? | Consumer Financial Protection Bureau”

Posted on

Pay Rent With a Credit Card Without Your Landlord Accepting Cards

Published for OnlineCheckWriter.com

Disclosure: This article was published as part of a paid partnership with OnlineCheckWriter.com, a Zil Money platform. The author is an independent contributor.

A landlord may prefer ACH, wire transfer, or a physical check even when the tenant wants to use a credit card.

That does not necessarily mean the landlord must start accepting card payments.

OnlineCheckWriter.com offers a card-funded rent payment workflow in which the payer can use an eligible credit card as the funding source while the landlord receives the rent through a supported delivery method. The payer’s funding method and the landlord’s receiving method can therefore be different. ([Check Writer][1])

How Does the Payment Work?

The process begins with the person making the rent payment.

The payer enters the landlord’s information, the rent amount, and the required payment details. The credit card is selected as the funding source.

The landlord does not need to process the card directly. Instead, the payment can be delivered through a supported method such as ACH, wire transfer, or a physical mailed check, depending on the selected workflow and applicable conditions.

This distinction is important.

The landlord is not necessarily receiving a credit-card transaction. The credit card is used on the funding side, while the landlord receives the rent using the chosen supported payment method.

Does the Landlord Need an OnlineCheckWriter.com Account?

The purpose of this workflow is to allow the payer to use a card without requiring the landlord to change how rent is normally received.

OnlineCheckWriter.com’s current product information states that the recipient does not have to begin accepting credit cards directly for the payer to use a supported card-funded workflow.

The payer should still confirm the landlord’s preferred payment method and make sure the correct bank or mailing information is entered before submitting the transaction.

Check Current Pricing Before You Pay

Credit-card-funded rent payments are not automatically free.

Processing fees and other charges may apply depending on the funding method, delivery option, account terms, and selected service.

Because pricing can change, businesses and individuals should review the current OnlineCheckWriter.com pricing and the fee displayed for the specific transaction before submitting the payment.

This is more reliable than using a percentage from an older article.

The practical question is whether the total cost makes sense for the reason the payer wants to use a credit card.

Consider the Card Terms Too

The payment platform fee is only one part of the decision.

The cardholder should also review the credit card’s available limit, billing cycle, payment due date, APR, grace-period conditions, and repayment requirements.

Using a credit card changes when the payer may need to use cash, but it does not eliminate the obligation to repay the card balance.

A card-funded rent payment should therefore be evaluated with a clear repayment plan.

What About Credit Card Rewards?

Some credit cards offer points, miles, or cash-back rewards on eligible transactions.

Whether a rent payment qualifies for rewards depends on the card issuer and the specific card program.

The payer should confirm eligibility directly with the issuer rather than assuming rewards will apply.

Any potential reward value should also be compared with the processing cost and other applicable charges.

Choose the Delivery Method Around the Landlord

The landlord’s preferred receiving method still matters.

ACH may work when the landlord provides the necessary bank information. A wire may be appropriate for certain transactions. A physical check may fit a landlord who prefers paper payments.

The payer should select the method that matches the landlord’s requirements and allows enough time for processing or delivery.

Submitting a payment and the landlord actually receiving or depositing it are separate stages.

Is Paying Rent by Credit Card the Right Choice?

Paying rent with a credit card without the landlord accepting cards directly can provide another funding option for eligible transactions.

It does not mean using a card is automatically the right choice every month.

Before paying, review the current processing cost, the landlord’s preferred delivery method, card terms, available credit, payment timing, and how the card balance will be repaid.

The useful question is not simply, “Can I pay rent with a credit card?”

It is, “Does using my card for this rent payment make sense after I understand the complete cost and repayment timing?”

OnlineCheckWriter.com – powered by Zil Money, is a financial technology company, not a bank. Banking and money movement services are provided through partner financial institutions and licensed service providers. FDIC insurance coverage applies only to eligible deposit products and accounts, and is subject to applicable terms, conditions, limitations, and requirements. Additional information regarding partner institutions, products, and services is available in the applicable terms and agreements.

[1]: https://onlinecheckwriter.com/pay-rent-with-credit-card/ “Pay Rent With Credit Card & Earn Rewards, Improve Cash Flow”

[2]: https://support.onlinecheckwriter.com/portal/en/kb/articles/how-much-is-by-default-credit-card-processing-fee “What is the credit card processing fee?”

Posted on

Landlord Doesn’t Accept Credit Cards? Funding and Delivery Can Be Different

Disclosure: This article was published as part of a paid partnership with OnlineCheckWriter.com, a Zil Money platform. The author is an independent contributor.

If your landlord doesn’t accept credit cards, that does not always mean an eligible rent payment must be funded directly from a checking account.

A payment intermediary can separate the payer’s funding source from the way the landlord receives the money.

OnlineCheckWriter.com currently supports an eligible card-funded workflow in which the payer uses a credit card while the landlord receives the rent through a supported method such as ACH, wire, or check.

The landlord does not need to process the card directly.

Understand the Funding and Delivery Difference

This is the central concept.

The business or renter uses the card to fund the transaction.

OnlineCheckWriter.com then sends the payment through the selected supported delivery method.

If the landlord normally accepts ACH, the landlord can receive ACH.

If the landlord requires a check, the payment can follow the applicable check-delivery workflow.

The payer’s card and the landlord’s payment method do not have to be the same.

There Is a Processing Fee

Card funding is not free.

OnlineCheckWriter.com’s current Pay by Credit Card page lists a 2.90% processing fee when the credit card is used as the funding source.

Businesses should check current pricing when making the transaction because fees and product terms can change.

Other charges may also depend on the payment method selected for the landlord.

The processing fee should therefore be part of the decision before the rent is charged to the card.

Supporting Documentation Is Required

OnlineCheckWriter.com’s current support documentation says credit-card transactions require supporting documents.

For rent, the support center identifies a rental agreement or invoice and also states that supporting lease documentation may need to be uploaded for each rent transaction.

That requirement should be understood before relying on the workflow for a deadline.

Do not wait until rent is due to discover that transaction documentation is needed.

Do Not Assume a Fixed Cash-Flow Period

Using a credit card changes when the payer must pay the card issuer, but that does not create a universal 30-day or 45-day extension.

The Consumer Financial Protection Bureau defines a grace period as the period between the end of the billing cycle and the payment due date. It also notes that issuers are not required to provide a grace period on every card.

The actual timing depends on the card’s statement cycle, due date, grace-period conditions, and whether a balance is being carried.

Check the specific card agreement.

Rewards Are Controlled by the Card Issuer

OnlineCheckWriter.com’s live Rent page currently uses strong language about earning rewards.

Whether a card-funded rent transaction earns cash back, points, miles, or another reward depends on the issuer and the card’s program rules.

OnlineCheckWriter.com cannot responsibly guarantee a reward outcome for every card.

The payer should check the issuer’s terms and compare any expected reward value with the 2.9% processing fee.

The Landlord’s Preference Still Matters

Even when the landlord does not accept cards, the payer still needs accurate landlord information.

For ACH, that can mean verified bank details.

For a mailed check, the correct payee and mailing address are important.

For a wire, the recipient’s wire instructions need to be correct.

Card funding does not remove the normal verification required for the delivery method.

Is This Workflow Useful?

It can be considered when an eligible payer specifically wants to use a card and the landlord accepts another supported payment method.

The reason might involve payment timing, an internal business-card strategy, or another legitimate financial-management consideration.

But the decision should account for the processing fee and the obligation to repay the credit-card balance.

If your landlord doesn’t accept credit cards, OnlineCheckWriter.com can provide a funding-versus-delivery workaround for eligible rent.

The accurate value proposition is payment flexibility, not guaranteed rewards, free financing, or automatic credit improvement.

OnlineCheckWriter.com – powered by Zil Money, is a financial technology company, not a bank. Banking and money movement services are provided through partner financial institutions and licensed service providers. FDIC insurance coverage applies only to eligible deposit products and accounts, and is subject to applicable terms, conditions, limitations, and requirements. Additional information regarding partner institutions, products, and services is available in the applicable terms and agreements.

Posted on

What to Do When You Run Out of Checks and a Payment Is Due

Disclosure: This article was published as part of a paid partnership with OnlineCheckWriter.com, a Zil Money platform. The author is an independent contributor.

If you are wondering what to do when you run out of checks, start with the payment deadline and what the recipient will accept.

Running out of a physical checkbook does not always mean the payment has to wait for a replacement order.

A business may have several options, including another payment method, temporary checks from the bank, on-demand check printing, or an electronically delivered printable check.

The right backup depends on the recipient and the urgency.

First Ask Whether a Check Is Actually Required

Before rebuilding the check process, contact the recipint.

A vendor that normally receives checks may be willing to accept ACH or wire for an urgent payment.

If the recipient is willing to provide the information required for another payment rail, that can remove the checkbook problem entirely.

Do not assume that “we normally pay by check” means “the vendor accepts only checks.”

The business should still compare fees, timing, and recipient requirements before changing the payment method.

Ask the Bank About Temporary Checks

If the recipient requires a physical check, the bank may have a short-term option.

Chase currently explains that banks may be able to issue temporary checks while customers wait for newly ordered checks.

These are commonly called counter checks.

Their availability, format, quantity, and fees vary between financial institutions.

Contact the bank directly before making a trip to the branch.

Print a Check on Demand

Another option is to create and print the check instead of ordering another pre-printed checkbook.

OnlineCheckWriter.com provides an on-demand workflow where an authorized user can enter the payee and amount, select the appropriate bank account, review the check, and print it on compatible stock.

This can be useful for businesses that already maintain a suitable check-printing setup.

It can also reduce dependence on separate pre-printed check supplies for every bank account.

Get the MICR Line Right

If you are printing the check yourself, understand how the MICR line will be produced.

The Federal Reserve says the MICR line contains information such as the bank routing number, account number, and check serial number.

When the payer prints that line, the Federal Reserve says it should be printed using magnetic ink.

If the MICR line is already pre-printed on the check stock, the remaining information can use regular ink.

This is one reason businesses should not treat check printing as simply printing a normal PDF on any available paper.

Consider Electronic Check Delivery

If the recipient wants a check but postal delivery is the main problem, OnlineCheckWriter.com’s eCheck workflow may be another option.

In OnlineCheckWriter.com terminology, an eCheck is a printable check sent electronically to the payee.

The recipient can print it and follow the check-deposit process accepted by the financial institution.

It is separate from ACH.

Receiving the document electronically also does not mean the funds have already cleared.

Do Not Let Urgency Create a Payment Mistake

Running out of checks can create pressure to solve the problem quickly.

Still verify the funding account, routing number, account number, payee, amount, check number, and delivery information.

If the company has an approval process, keep it.

A rushed duplicate payment or wrong-account check creates a bigger problem than waiting a few extra minutes to verify the transaction.

Build a Backup Before It Happens Again

Once the urgent payment is handled, decide how the business will respond next time.

That might mean keeping appropriate blank check stock available, knowing how to request bank counter checks, setting up an on-demand check-printing platform, or establishing approved ACH and wire alternatives for recurring vendors.

The best answer to what to do when you run out of checks is not simply “order more.”

It is to choose the payment method that meets the deadline and recipient requirement while keeping bank information, authorization, printing requirements, and payment records under control.

OnlineCheckWriter.com – powered by Zil Money, is a financial technology company, not a bank. Banking and money movement services are provided through partner financial institutions and licensed service providers. FDIC insurance coverage applies only to eligible deposit products and accounts, and is subject to applicable terms, conditions, limitations, and requirements. Additional information regarding partner institutions, products, and services is available in the applicable terms and agreements.